Calculating Lost Wages and Medical Expenses in Settlement
Master the calculation of lost wages and medical expenses in settlement claims. Call (833)-632-1198 for a free case review to maximize your recovery.
By Camden Roth
A car accident can upend your life in an instant. Beyond the physical pain and emotional toll, you face a mountain of bills, lost income, and an insurance system that often seems designed to minimize your recovery. If you are pursuing a personal injury claim, understanding how to calculate lost wages and medical expenses in settlement negotiations is critical to ensuring you receive fair compensation. These two categories, economic damages, are the foundation of most settlement demands because they are quantifiable and easier to prove than pain and suffering. Yet many injury victims accept lowball offers because they underestimate their own losses or fail to document them properly. This guide will walk you through the process step by step, from gathering evidence to negotiating with adjusters, so you can approach your claim with confidence and clarity.
What Are Economic Damages in a Personal Injury Case?
Economic damages are the financial losses you can calculate with receipts, pay stubs, and medical records. They stand in contrast to non-economic damages, such as pain and suffering, emotional distress, and loss of enjoyment of life, which are subjective and harder to quantify. In most personal injury settlements, lost wages and medical expenses form the bulk of the economic damages claim.
Lost wages include not only the income you have already missed due to your injuries but also future earning capacity you may lose if you cannot return to your previous job or work the same number of hours. Medical expenses cover everything from emergency room visits and surgeries to physical therapy, prescription medications, and assistive devices. In some cases, you may also claim travel costs for medical appointments and the value of household services you can no longer perform.
Insurance adjusters are trained to scrutinize these claims. They will look for gaps in documentation, pre-existing conditions, and any reason to argue that your losses are exaggerated. That is why building a thorough, well-organized record from day one is essential. If you are working with an attorney, they can help you identify all recoverable losses and present them persuasively. For those still searching for representation, resources like how law firm reputation affects settlement offers can shed light on why choosing the right advocate matters.
Calculating Lost Wages: Past and Future Income
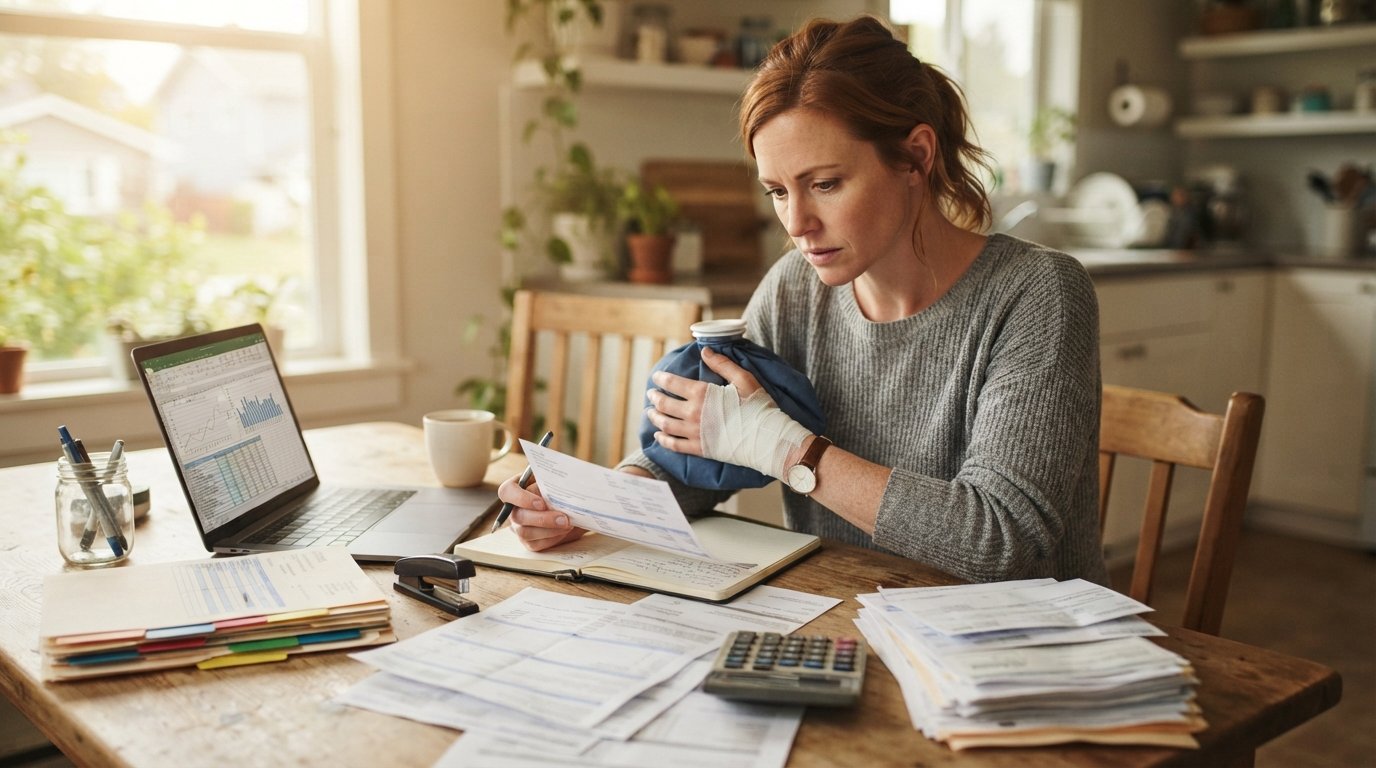
Lost wages are often the most straightforward economic damage to calculate, but only if you have the right documentation. Start by determining your average daily or weekly income before the accident. This includes your base salary or hourly wage, overtime, bonuses, commissions, and tips. If you are self-employed, you will need profit and loss statements, tax returns, and client invoices to establish your income.
Once you have your pre-accident earnings, tally the time you have missed from work due to your injuries, medical appointments, and recovery. This includes not only full days but also partial days if you had to leave early or arrive late. If your employer offers paid sick leave or vacation time that you were forced to use, you can typically still claim those hours as lost wages because you lost the benefit of that paid time off.
Future lost wages, also called loss of earning capacity, are more complex. If your injuries prevent you from returning to your old job or force you to work fewer hours, you can claim the difference between what you would have earned and what you can now earn. This often requires testimony from a vocational expert or economist who can project your future earnings based on your age, education, skills, and the nature of your disability.
Here is a simple framework to calculate past lost wages:
- Determine your gross weekly income before the accident (including overtime and bonuses).
- Count the number of workdays or hours you missed because of the injury.
- Multiply your daily or hourly rate by the time missed.
- Subtract any sick pay or disability benefits you received that were not paid by you (though you may need to reimburse those providers).
- Add any lost self-employment income, such as canceled contracts or lost clients.
Keep in mind that some states require you to use net income (after taxes) rather than gross income for lost wage claims. An experienced attorney can advise you on your state's specific rules.
Documenting Medical Expenses for Your Settlement
Medical expenses are often the largest component of a personal injury settlement. They include all past and future costs related to treating your injuries. To maximize your recovery, you must document every expense thoroughly and link each one to the accident.
Start by requesting itemized bills from every provider you have seen: emergency room, hospital, specialists, physical therapists, chiropractors, and pharmacies. These bills should show the date of service, the procedure or treatment code, and the amount charged. If you have health insurance, you will also need the explanation of benefits (EOB) statements that show what the insurer paid and what you owe. Even if your health insurer covered most of the cost, you can often claim the full billed amount as damages, though you may have to repay the insurer from your settlement.
Future medical expenses are those you will reasonably need down the road. They might include ongoing physical therapy, future surgeries, pain management, or prescription medications. To prove these, you will need a letter from your treating physician outlining the recommended care, the frequency, and the estimated cost. In some cases, a life care planner can create a comprehensive projection of all future medical needs and their costs.
Do not overlook incidental expenses. These can include:
- Medical equipment such as crutches, wheelchairs, braces, or heating pads.
- Prescription and over-the-counter medications.
- Mileage to and from medical appointments (often reimbursed at a standard IRS rate).
- Home modifications, such as ramps or grab bars, if required by your injuries.
- Household services you can no longer perform, like cleaning, yard work, or childcare.
Each of these items should be backed by receipts, invoices, or a physician's recommendation. The more detailed your records, the harder it is for an adjuster to dispute them.
Gathering Evidence: Pay Stubs, Tax Returns, and Medical Records
Evidence is the currency of settlement negotiations. Without it, your claim is just a story. For lost wages, you will need pay stubs covering the period before the accident and the period you missed work. If you are salaried, a letter from your employer confirming your salary and the dates you were absent can be helpful. For self-employed individuals, tax returns for the past two to three years, along with profit and loss statements and client affidavits, will establish your income.For medical expenses, you will need a complete set of medical records from every provider, including doctor's notes, test results, and treatment plans. These records should clearly state that your injuries were caused by the accident and that the treatment was necessary. If there are gaps in treatment, be prepared to explain them (for example, you could not afford a specialist or you were waiting for insurance approval).
It is also wise to keep a daily journal documenting your pain levels, limitations, and any out-of-pocket expenses. While not a substitute for formal records, a journal can humanize your claim and support your credibility.
Working with Experts to Strengthen Your Claim
In complex cases, expert witnesses can make a significant difference in calculating lost wages and medical expenses in settlement. An economist can calculate the present value of future lost earnings, accounting for inflation and raises you would have received. A vocational expert can assess your transferable skills and determine what jobs you can realistically perform after your injury. A life care planner can itemize future medical needs and their costs.
These experts do not come cheap, but their reports can substantially increase your settlement, especially if your case goes to mediation or trial. Your attorney will typically advance these costs and recoup them from your settlement.
If you are still looking for legal representation, consider reaching out to a service that connects injury victims with qualified attorneys. For example, AutoInjuryAccident offers a free, confidential case review for people injured in car crashes, truck wrecks, and other accidents. They are not a law firm but can help you explore your options with participating attorneys nationwide.
Negotiating with Insurance Adjusters
Insurance adjusters are not on your side. Their job is to settle your claim for as little as possible. When you present your lost wage and medical expense calculations, they will look for reasons to reduce them. Common tactics include arguing that your treatment was excessive, that your injuries pre-existed the accident, or that you failed to mitigate your damages by returning to work too soon or too late.
To counter these tactics, you need a well-organized demand package that tells a compelling story. Start with a cover letter summarizing the accident, your injuries, and the total damages. Then include sections for medical expenses (with bills and records), lost wages (with pay stubs and employer letters), and future losses (with expert reports). Be transparent about any pre-existing conditions and explain how the accident aggravated them.
Do not accept the first offer. Insurance companies often leave room for negotiation. If the adjuster disputes specific charges, ask for a written explanation and provide additional documentation. If negotiations stall, you may need to file a lawsuit to force a better settlement. Many cases settle after litigation begins because the insurance company realizes you are serious.
Common Mistakes That Reduce Settlements
Even well-intentioned claimants can hurt their own cases by making avoidable mistakes. One of the most common is failing to document lost wages properly. If you are paid under the table or work as a gig worker, you may not have traditional pay stubs, but you can still prove income through bank statements, 1099 forms, and client records. Do not simply estimate your losses; provide evidence.
Another mistake is waiting too long to seek medical treatment. Insurance adjusters argue that a gap in treatment means you were not seriously injured. If you cannot afford care, look for clinics that accept liens or sliding-scale payments. Your health and your claim both depend on consistent treatment.
Finally, do not post about your accident or injuries on social media. Defense attorneys and adjusters routinely review public profiles for photos or comments that contradict your claim. Even a picture of you smiling at a family gathering can be taken out of context. The safest approach is to stay off social media until your case is resolved.
When to Hire an Attorney for Your Settlement
You can negotiate a personal injury settlement on your own, but the process is full of traps for the unwary. If your case involves significant lost wages, ongoing medical treatment, or disputed liability, an attorney can level the playing field. Most personal injury attorneys work on a contingency fee basis, meaning they only get paid if you win. This aligns their interests with yours and removes the financial barrier to representation.
An attorney can also help you calculate damages you might not have considered, such as loss of consortium for a spouse or loss of enjoyment of life. They can hire experts, file lawsuits, and negotiate from a position of strength. Studies consistently show that injury victims who hire attorneys receive higher settlements, even after attorney fees are deducted.
If you are unsure whether you need a lawyer, consider a free consultation. Many firms offer them, and you can get a professional assessment of your case without obligation. Platforms like LawyerOffer can connect you with attorneys who specialize in your type of claim.
Putting It All Together: A Step-by-Step Approach
Calculating lost wages and medical expenses in settlement is not just about math; it is about building a persuasive case. Follow these steps to maximize your recovery:
- Seek immediate medical attention and follow your doctor's orders.
- Document everything: keep a file with bills, pay stubs, receipts, and records.
- Calculate past lost wages using your pre-accident income and missed time.
- Project future lost wages with help from a vocational or economic expert.
- Itemize all past and future medical expenses, including incidental costs.
- Prepare a demand letter that clearly presents your damages and supporting evidence.
- Negotiate with the adjuster, and be prepared to litigate if necessary.
Remember that every case is unique. What works in one settlement may not work in another. The key is to be thorough, patient, and persistent. With the right evidence and a clear understanding of your losses, you can achieve a fair resolution.
If you are ready to take the next step, consider reaching out to a legal professional who can help you navigate the complexities of your claim. Whether you need assistance calculating lost wages, understanding medical liens, or negotiating with insurers, having an advocate on your side can make all the difference. Do not let the insurance company dictate the value of your injuries. Take control of your settlement today.