Denied Homeowners Insurance Claim: Steps to Appeal in 2026
Facing a denied homeowners insurance claim? Learn the steps to appeal and maximize your recovery. Call (833)-632-1198 for a free case review.
By Michael Turner
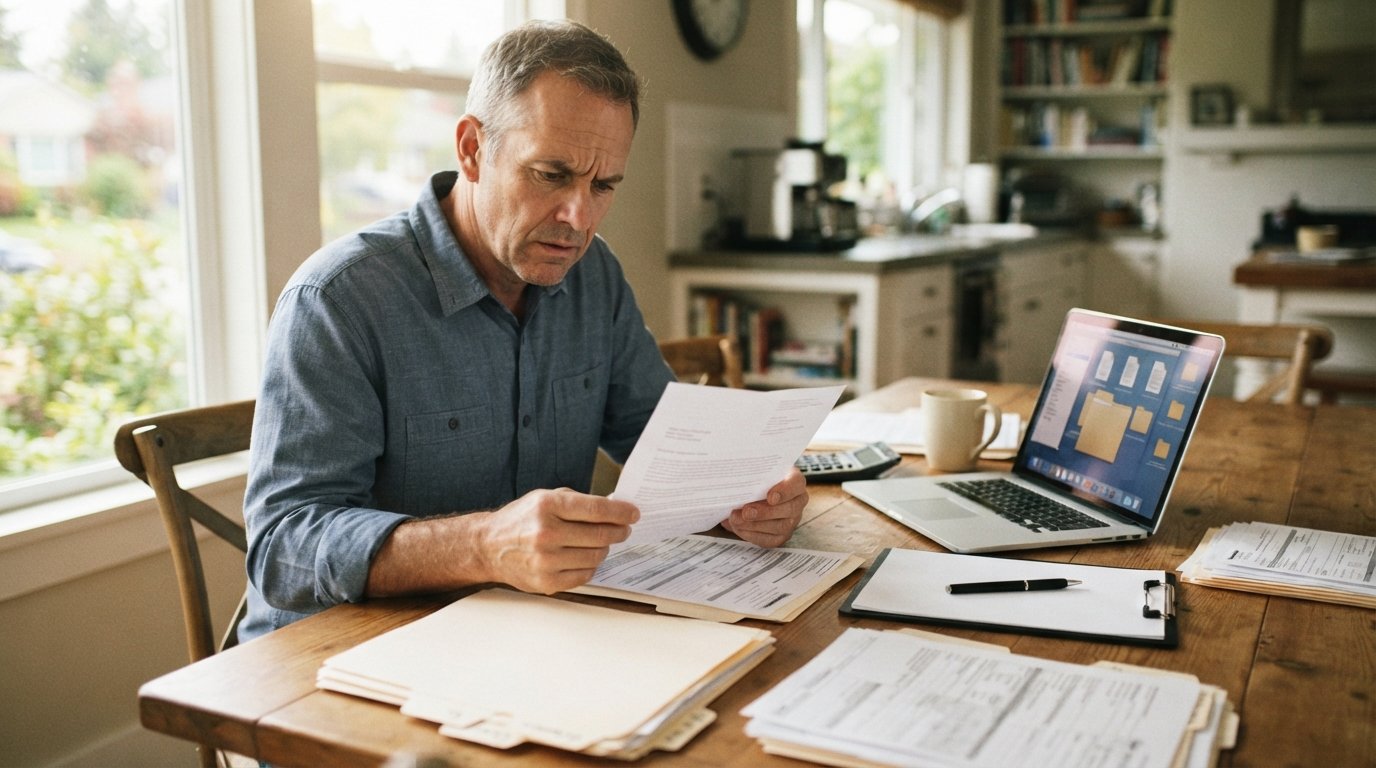
Your home is likely your largest investment, so a denied insurance claim can feel like a devastating blow. Whether the denial is due to a disputed cause of loss, insufficient documentation, or an insurer's error, you are not powerless. The denial is not the final word. With a clear strategy and the right documentation, you can challenge the decision and potentially recover the funds needed to repair or rebuild. This guide walks you through the denied homeowners insurance claim steps to appeal, from internal reviews to legal options, so you can fight back effectively.
Why Homeowners Insurance Claims Get Denied
Before you appeal, it helps to understand why the insurer said no. Common reasons include:
- Policy exclusions: The damage may be explicitly excluded, such as flood or earthquake damage in a standard policy.
- Lack of maintenance: Insurers may argue the damage resulted from neglect, such as a leaking roof that was not repaired.
- Insufficient proof: You may not have provided enough evidence to prove the loss occurred as described.
- Filing errors: Missed deadlines or incorrect forms can lead to denial.
- Bad faith: In some cases, the insurer may deny a valid claim to save money, which is illegal.
Understanding the specific reason for denial is the first step in building a successful appeal. Review the denial letter carefully. It should state the policy provision relied upon and the factual basis for the decision. If the letter is vague, request clarification in writing.
Step 1: Review Your Policy and the Denial Letter
Start by pulling out your homeowners insurance policy. Read the sections on coverage, exclusions, and conditions. Compare the denial letter's reasoning against the policy language. Sometimes the insurer misinterprets its own policy or overlooks a provision that favors you. For example, if the denial cites "wear and tear," but the damage was sudden and accidental, you may have grounds to appeal.
Also, check whether the insurer followed the claims handling procedures required by your state. Many states have regulations that mandate timely communication and fair investigation. If the insurer missed deadlines or failed to conduct a thorough investigation, that can strengthen your appeal. Document everything: the date you filed the claim, the date of the denial, and any correspondence. Keep a claim diary.
Step 2: File an Internal Appeal with Supporting Documentation
The first formal step in the appeal process is usually an internal appeal to the insurance company. This involves submitting a written request for reconsideration along with additional evidence. Your goal is to make it easy for the adjuster to reverse the decision. Here is how to structure your appeal:
- Write a formal appeal letter: Address it to the claims manager or the person who signed the denial letter. Include your policy number, claim number, and date of loss. Clearly state that you are appealing the denial and why you believe it is wrong. Be polite but firm.
- Provide new evidence: This could include a contractor's estimate, photographs, video, receipts, or a professional report (e.g., from an engineer or roofer) that contradicts the insurer's findings. If the denial was based on a lack of proof, this is your chance to fill the gaps.
- Cite policy language: Quote the specific sections of your policy that support coverage. Explain how the facts of your loss fit within those provisions.
- Request a re-inspection if needed: If the insurer's adjuster missed damage or made errors, ask for a second inspection. You can also hire your own independent adjuster to document the damage. An independent adjuster works for you, not the insurer, and can provide a detailed report that carries weight.
- Set a deadline: Ask for a written response within a specific timeframe, such as 30 days. This puts pressure on the insurer to act.
Send your appeal via certified mail with return receipt requested, and keep a copy. This creates a paper trail. If the insurer does not respond or denies again, you can escalate.
If your case involves complex causation issues, such as distinguishing between wind and flood damage, consider obtaining an expert opinion. For example, a roofing contractor can attest that the damage was caused by wind, not age. This kind of evidence can be pivotal.
Step 3: Request a Re-Inspection or Independent Adjuster Review
Sometimes the denial stems from a disagreement about the extent or cause of damage. In that case, a re-inspection can be a game-changer. You can ask the insurer to send a different adjuster, or you can hire a public adjuster to represent you. Public adjusters are licensed professionals who work on your behalf to document and negotiate claims. They typically charge a percentage of the settlement, but they can level the playing field.
If you hire an independent adjuster, share their report with the insurer and request that they reconsider based on the new evidence. Many insurers will reverse a denial when faced with a well-documented professional opinion. In some states, you have the right to request an appraisal if the dispute is solely about the amount of loss, not coverage. The appraisal process involves each side hiring an appraiser, and if they disagree, a neutral umpire decides. This can be faster and cheaper than litigation.
Step 4: File a Complaint with the State Department of Insurance
If the internal appeal fails, your next step is to involve the state. Every state has a department of insurance that regulates insurers and handles consumer complaints. Filing a complaint is free and can prompt the insurer to take another look, especially if they have a pattern of bad behavior.
To file a complaint, visit your state's department of insurance website and complete the online form. You'll need to provide details about your claim, the denial, and copies of your correspondence. The department will contact the insurer and request a response. While the department cannot force the insurer to pay, it can investigate and sometimes mediate a resolution. It also creates a record that can be useful if you later sue for bad faith.
Be aware that the department's review may take weeks or months. Use this time to continue gathering evidence and exploring other options.
Step 5: Consult an Attorney About a Bad Faith Denial
If your insurer denied a valid claim without a reasonable basis, you may have a claim for bad faith. Bad faith laws vary by state, but generally, an insurer must act in good faith and deal fairly with policyholders. If they unreasonably delay, deny, or underpay a claim, they can be liable for damages beyond the policy limits, including emotional distress and punitive damages.
Consulting an attorney is especially important if:
- The denial was based on a misinterpretation of policy language.
- The insurer ignored your evidence or failed to investigate.
- You suffered significant financial harm due to the delay.
- The insurer made a lowball offer that you believe is unfair.
An experienced insurance claims attorney can review your case, send a demand letter, and if necessary, file a lawsuit. Many attorneys offer free consultations and work on a contingency fee basis, meaning you pay nothing unless they recover money for you. If you are considering legal action, it's wise to act promptly because statutes of limitations apply. For those seeking to connect with qualified legal professionals, platforms like AttorneyLeads can facilitate introductions to attorneys specializing in insurance disputes.
In some cases, hiring an attorney can lead to a faster and larger settlement because insurers know that policyholders with legal representation are more likely to fight back. Even if you don't go to court, the threat of litigation can push the insurer to reconsider.
How AI Is Changing the Appeals Process
Technology is increasingly playing a role in insurance claims. Insurers use AI to triage claims and detect fraud, but policyholders can also leverage technology. For example, apps can help you document damage with time-stamped photos and videos. Some legal tech platforms use AI to analyze policy language and predict claim outcomes. As we move into 2026, expect more tools that help consumers understand their rights and automate parts of the appeal process. However, human judgment remains critical, especially when dealing with complex coverage disputes. For a deeper look at how AI is used in claim processing, see our guide on how AI is used in insurance claim processing.
Key Takeaways for a Successful Appeal
Appealing a denied homeowners insurance claim requires persistence and organization. Here are the most important points to remember:
- Act quickly: Many policies and state laws have strict deadlines for appeals.
- Document everything: Keep copies of all correspondence and evidence.
- Get professional help: Contractors, public adjusters, and attorneys can provide credible evidence.
- Escalate strategically: Move from internal appeal to state complaint to legal action if necessary.
- Don't give up: Insurers often reverse denials when faced with a determined policyholder.
Remember, the denial is not the end. By following these steps, you can increase your chances of getting the compensation you deserve. If you need help finding an attorney to handle your appeal, consider using a service like LawyerOffer.com, which connects consumers with qualified legal professionals for free case reviews. With the right approach, you can turn a denial into a successful claim.