Future Medical Care Damages in Accident Claims: 2026 Guide
Understand future medical care damages in accident claims and how to pursue them. Call 8336321198 for a free case review.
By Soraya Whitcombe
When a serious injury occurs in an accident, the financial fallout rarely ends when you leave the hospital. Surgeries, ongoing physical therapy, prescription medications, and future medical monitoring can stretch for years or even decades. These anticipated expenses fall under a specific legal category known as future medical care damages in accident claims. Understanding how courts calculate these damages is essential for anyone pursuing fair compensation, because insurers routinely undervalue or dispute long term care costs. Whether you are negotiating a settlement or preparing for trial, a clear grasp of future medical damages can mean the difference between a recovery that covers your needs and one that leaves you paying out of pocket for care you never expected.
What Are Future Medical Care Damages in Accident Claims?
Future medical care damages represent the estimated cost of all medical treatment you will reasonably need after the date of your settlement or trial. Unlike past medical bills, which are documented by receipts and records, future damages require projection. They encompass a wide range of services, from routine follow up visits to complex surgical procedures that may become necessary as your condition evolves. The key legal standard is reasonable medical probability: you must show that the future care is more likely than not to be required because of the accident.
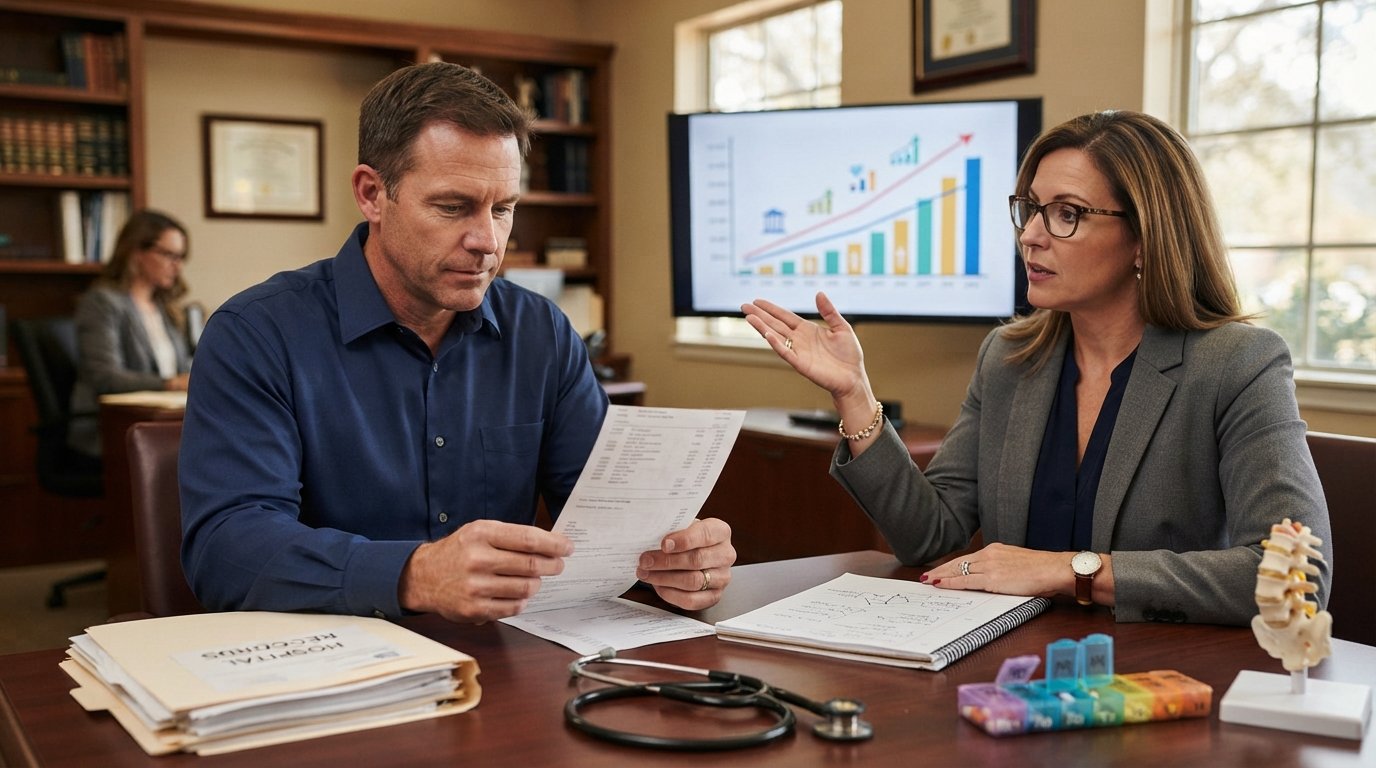
These damages are not speculative. They must be supported by expert testimony, typically from treating physicians and life care planners who analyze your condition, prognosis, and anticipated treatment trajectory. A life care plan, for example, might itemize costs for annual neurology appointments, mobility equipment replacements, and home health aide services over your expected lifespan. Without such evidence, an insurer will argue that your future needs are guesswork and offer little or nothing for them.
The distinction between past and future medical damages matters because different proof rules and valuation methods apply. Past expenses are usually proven with billing records and expert testimony about reasonableness. Future expenses rely on medical projections and economic calculations that account for inflation and your specific life expectancy. If you are also dealing with a commercial vehicle crash, the complexities multiply, as we explain in our guide on why truck accident claims differ from car accident cases. The same principle holds: the more severe the injury, the more critical it is to document and project future care accurately.
How Courts and Insurers Calculate Future Medical Costs
Calculating future medical care damages involves a blend of medical and economic expertise. The process generally begins with your treating physician outlining the expected course of treatment. That narrative is then translated into a dollar figure by a life care planner or economist who applies current costs and adjusts for inflation, discount rates, and your projected lifespan. Insurers often challenge each component, arguing that certain treatments are unnecessary, too far in the future, or not causally related to the accident.
Several factors heavily influence the final number. The severity and permanence of your injury top the list: a spinal cord injury with lifetime paralysis will generate far higher future costs than a fractured arm that heals completely. Your age and pre existing conditions also matter, because they affect both life expectancy and the likelihood of complications. Geographic location plays a role too, since medical costs vary widely by region. Finally, the quality and credibility of your expert witnesses can sway a jury or adjuster.
To build a persuasive claim, your attorney will typically gather the following evidence:
- Detailed narrative reports from treating physicians describing your prognosis and recommended future treatments.
- A formal life care plan that itemizes every anticipated service, device, and medication with projected frequencies and costs.
- Medical literature and clinical guidelines supporting the necessity of the recommended care.
- Economic expert reports that calculate present value and account for inflation over your lifetime.
Each piece of evidence must be tailored to your specific situation. A generic estimate will not survive an insurer's scrutiny. For example, if your doctor recommends annual MRI scans for the rest of your life, the life care plan must state the current cost per scan, the expected number of scans based on your life expectancy, and the inflation factor. Any gap in that chain gives the defense an opening to reduce the award.
Even with strong evidence, negotiations can stall. Insurers often have internal guidelines that cap future medical payouts regardless of the merits. That is why many claimants turn to legal professionals who understand how to pressure insurers and present a compelling case. Platforms like LawyerCaseReview connect individuals with attorneys experienced in personal injury and mass tort litigation, offering a way to get case evaluations without upfront cost. Having the right advocate can make a measurable difference in how future medical damages are valued.
Common Challenges in Proving Future Medical Needs
Proving future medical care damages is rarely straightforward. One major hurdle is the requirement of reasonable medical probability. You cannot simply assert that you might need surgery someday; you must show that it is more likely than not. This standard forces claimants to rely on credible medical experts who can articulate why a particular treatment is necessary and not merely precautionary. Judges and juries are skeptical of speculative claims, so the quality of your medical proof is paramount.
Another challenge is the causation link. Insurers frequently argue that your future needs stem from a pre existing condition or natural aging rather than the accident. For example, if you had mild arthritis before the crash and now need a knee replacement, the defense may claim the surgery was inevitable. Your attorney must present medical testimony that distinguishes accident related damage from unrelated degeneration. This often requires a thorough review of your medical history and a physician's opinion that the accident accelerated or worsened your condition.
Malingering accusations also arise. Defense experts may suggest you are exaggerating symptoms to inflate the claim. To counter this, your legal team can use surveillance, social media evidence, and independent medical examinations to demonstrate consistency in your reported limitations. Ironically, the same tools insurers use to undermine claims can be used to verify your credibility. A well documented history of complaints and treatment adherence strengthens your position.
Finally, life expectancy disputes are common. If you have a shorter than average life expectancy due to age or illness, the defense will argue that future care costs should be reduced accordingly. Conversely, if you are young and healthy, the projection may span decades, leading to a large number. Economists and life care planners must use reliable actuarial tables and be prepared to defend their assumptions under cross examination.
Steps to Strengthen Your Future Medical Damages Claim
Building a robust claim for future medical care damages requires early and consistent effort. The steps below outline a practical approach that can help you avoid common pitfalls and maximize your recovery.
- Seek continuous medical treatment. Gaps in care are often used to argue that you are not as injured as you claim. Follow your doctor's recommendations and keep all appointments, even if you feel better.
- Document everything. Keep a journal of symptoms, medications, and side effects. Save receipts, bills, and explanations of benefits. This record becomes the foundation for your life care plan.
- Consult a life care planner early. A planner can work with your physicians to outline future needs while your treatment is ongoing, rather than waiting until the end of your case.
- Hire an experienced attorney. A lawyer who regularly handles future medical damages will know which experts to retain and how to present their findings persuasively.
- Be honest with your providers. Exaggerating symptoms can destroy your credibility. Consistency and honesty are your best assets.
Following these steps does not guarantee a specific outcome, but it significantly improves your chances of a fair settlement. Insurers respect claimants who are organized, consistent, and represented by counsel. When they see a well prepared case, they are more likely to make a reasonable offer rather than risk a larger verdict at trial.
The Role of Experts in Valuing Future Medical Care
Experts are the backbone of any future medical damages claim. Treating physicians provide the clinical foundation by explaining your diagnosis, prognosis, and the treatments you will likely need. They must be willing to testify that the future care is reasonable and necessary. Some physicians are hesitant to project far into the future, so your attorney may need to retain a specialist who can speak to long term outcomes.
Life care planners take the physician's recommendations and translate them into a detailed, costed plan. They research the actual prices of medications, therapies, and equipment in your area. They also account for the frequency of each service, such as three physical therapy sessions per week for two years, followed by monthly maintenance sessions indefinitely. The planner's report becomes a roadmap for the jury or adjuster.
Economists then calculate the present value of the life care plan. They apply a discount rate to account for the fact that a lump sum awarded today can be invested to generate future returns. They also factor in inflation for medical costs, which historically rise faster than general inflation. The interplay between discount rates and inflation assumptions can be hotly contested, so a credible economist is essential.
In some cases, vocational experts may also be needed if your injury affects your ability to work. While not directly related to medical care, lost earning capacity often accompanies future medical needs. A vocational expert can assess your transferable skills and the impact of your limitations on your future employment, adding another layer of damages to your claim.
How Future Medical Damages Affect Settlement Negotiations
Future medical care damages often represent the largest portion of a serious injury claim. Insurers know this and may try to settle early, before you have a clear picture of your long term needs. Accepting a quick settlement can be disastrous if you later discover that you need additional surgeries or ongoing therapy that the settlement does not cover. Once you sign a release, you generally cannot reopen the claim for more money.
During negotiations, your attorney will present the life care plan and economic report to the adjuster. The goal is to justify a settlement figure that includes the present value of all future care. Insurers may counter with arguments that some treatments are unnecessary or that you will improve more than your doctors predict. Skilled negotiators use medical evidence, depositions, and the threat of trial to push for a fair number.
If the case proceeds to litigation, the jury will decide the amount. Juries tend to be sympathetic to plaintiffs with credible medical proof, but they can also be unpredictable. Your attorney's ability to simplify complex medical and economic testimony is crucial. Visual aids, such as charts showing the projected costs over time, can help jurors understand the magnitude of your needs.
Mediation is another common path. A neutral mediator helps both sides reach a compromise. Because mediation is non binding unless an agreement is signed, it offers a chance to settle without the risks of trial. Many personal injury cases, including those involving future medical damages, resolve through mediation.
Recent Legal Trends and Their Impact on Future Care Claims
Several legal trends are shaping how future medical care damages are handled in 2026. One notable development is the increasing use of artificial intelligence in insurance claims processing. Insurers are deploying AI to analyze medical records and predict future costs, sometimes with algorithms that undervalue complex injuries. Claimants and their attorneys must be prepared to challenge these automated assessments with human expert testimony.
Another trend is the push for transparency in medical pricing. New regulations in some states require hospitals to publish negotiated rates, which can help life care planners obtain more accurate cost data. However, the patchwork of state laws means that the quality of pricing information varies widely. Attorneys must adapt their evidence to the jurisdiction.
Telemedicine has also become more prevalent, affecting both the delivery of care and the calculation of future damages. Some follow up visits that once required travel can now be done virtually, potentially reducing costs. Yet telemedicine may not be appropriate for all specialties, so the impact on future damages is case specific. Experts must consider whether virtual care is a reasonable substitute for in person treatment.
Finally, mass tort litigation continues to influence personal injury law. Cases involving defective drugs or medical devices often involve large numbers of plaintiffs with similar future medical needs. Coordinated discovery and bellwether trials can set benchmarks for future care damages. If you are involved in a mass tort, understanding how those cases value future medical care is essential. LawyerOffer provides resources and connections for individuals navigating these complex claims, offering a free case review to help you understand your options.
Staying informed about these trends can give you an edge in negotiations. Insurers are constantly updating their playbooks, and your legal team should be doing the same.
Frequently Asked Questions About Future Medical Damages
Can I recover future medical damages if I have health insurance?
Yes. The fact that you have health insurance does not eliminate the at fault party's responsibility for your future care. However, the collateral source rule, which prevents defendants from reducing damages based on insurance payments, varies by state. In some jurisdictions, insurers may have a right of reimbursement from your settlement. An attorney can explain how these rules apply in your case.
What if my condition improves after settlement?
If you settle and later improve, you generally cannot be forced to return the money for future medical care you no longer need. Conversely, if you worsen, you cannot go back for more unless the settlement specifically reserved that right (which is rare). This is why accurate projection is so important. Underestimating future needs can leave you without recourse.
How long does it take to resolve a claim involving future medical damages?
These cases often take longer than simple injury claims because they require extensive expert work. It may take months to develop a life care plan and economic report. Negotiations or litigation can add additional time. While there is no fixed timeline, a reasonable estimate for a complex case is one to three years from filing to resolution.
Do I need a lawyer to pursue future medical damages?
While you can theoretically represent yourself, the complexity of proving future medical needs makes legal representation highly advisable. Insurers have teams of lawyers and experts working to minimize payouts. An experienced attorney can level the playing field and help ensure that your future care is fully accounted for. LawyerOffer offers a free, no obligation case review to connect you with qualified attorneys in your area.
Understanding future medical care damages is a critical step toward securing your financial stability after a serious accident. The costs of long term care can be overwhelming, but with the right evidence and representation, you can pursue the compensation you deserve. Take the time to document your needs, consult professionals, and explore your legal options. A well prepared claim not only addresses today's bills but also protects your health and finances for years to come.