Homeowners Insurance Claim Undervalued? Steps to Take
An undervalued homeowners insurance claim can be challenged with contractor bids, appraisal, and supplements. Call (833)-632-1198 for a free case review.
By Audra Bellrose
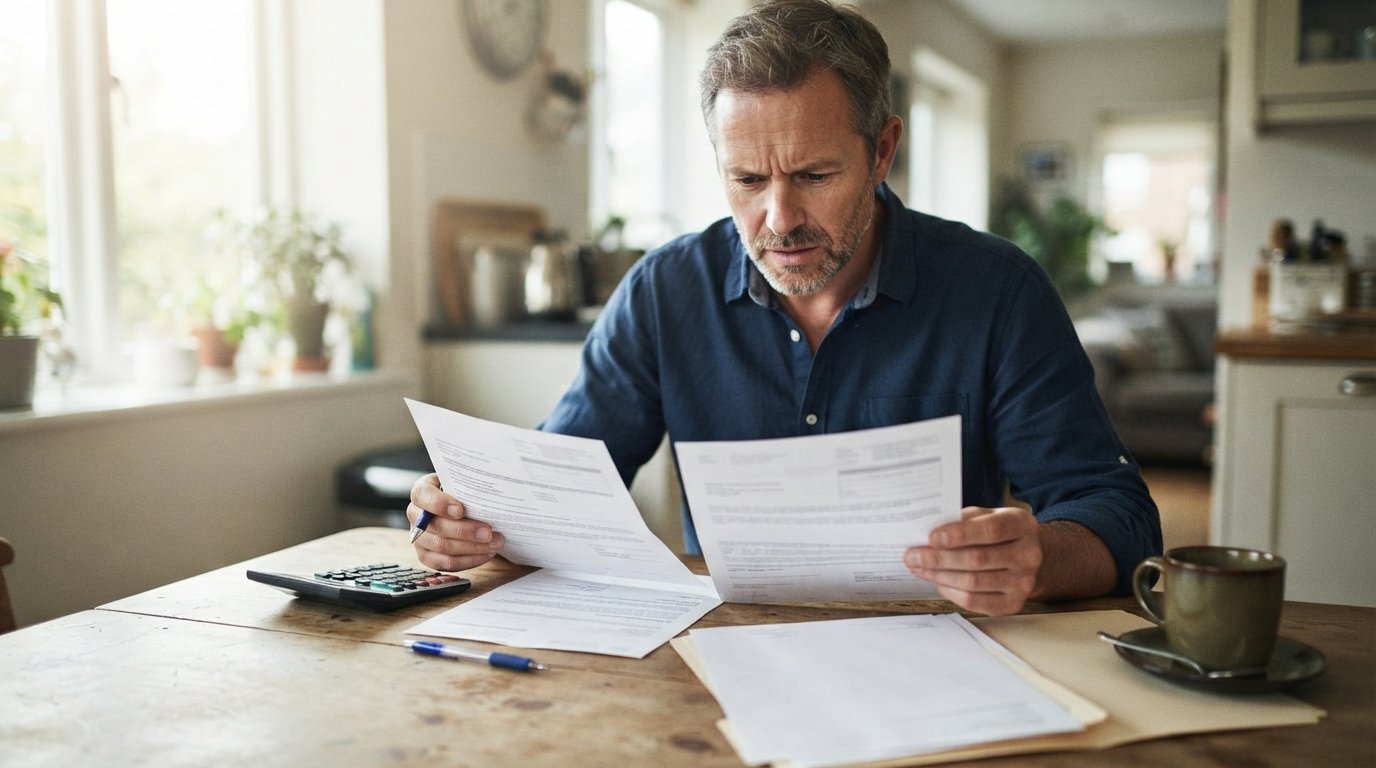
You open the settlement letter expecting it to cover the full cost of repairing your home, and the number on the page falls far short of what your contractor quoted. The check feels like a lowball offer, and you are not sure whether you have any leverage to push back. The good news is that you do. Insurance claims are negotiable, and policyholders who understand the process routinely recover thousands of dollars more than the initial offer. Whether the gap stems from missed damage, outdated pricing, or a genuine dispute over scope, there are concrete steps you can take to challenge an undervalued homeowners insurance claim and get the funds you need to restore your property.
Start by Understanding Why the Offer Came In Low
Before you fire off an angry email to your adjuster, take a breath and study the estimate line by line. Insurance adjusters are not necessarily trying to cheat you; many are overworked, use standardized pricing software, and rely on quick visual inspections that miss hidden damage. Common reasons a homeowners claim gets undervalued include missing line items for labor or materials, depreciation applied too aggressively, damage that was not visible during the initial inspection, and pricing that does not reflect your local market. Understanding the root cause helps you build a targeted rebuttal instead of a vague complaint.
Request a copy of the full adjuster report if you do not already have one. Compare it against your own records and any contractor bids you have collected. Look for specific categories where the numbers diverge, such as roofing squares, drywall square footage, or the cost of matching materials. When you can point to a specific line item and show why it is wrong, you are far more likely to get a productive response than if you simply assert that the offer is too low.
Compare the Adjuster Estimate Against Independent Contractor Bids
The single most effective tool in an undervalued claim dispute is a detailed, written estimate from a licensed contractor who has inspected the property. The adjuster works for the insurer, but your contractor works for you and has no incentive to minimize the scope of repairs. Ask two or three local contractors to provide line-item bids that mirror the format of the insurance estimate so the two documents can be compared side by side. The gap between the bids often reveals exactly where the insurer cut corners.
When you submit contractor bids, include photos, measurements, and any code upgrade requirements that the adjuster may have overlooked. For example, if your home was built before current building codes, the insurer may be obligated to pay for code upgrades that bring the repair into compliance. Many policies include ordinance or law coverage that pays for these upgrades, but adjusters frequently forget to apply it. A contractor who knows local codes can flag these items for you.
Keep in mind that the insurer is not required to pay the highest bid you receive. It is required to pay the reasonable cost to repair or replace your home with like kind and quality. If one contractor bids $80,000 and another bids $55,000 for the same scope, the insurer will likely lean toward the lower number. The goal is to demonstrate that the adjuster's number is unreasonably low, not simply that a more expensive option exists.
Invoke the Appraisal Clause for Valuation Disputes
Most homeowners policies contain an appraisal clause, a contractual provision that lets either party demand an independent valuation when they disagree on the amount of loss. This is not the same as going to court; appraisal is a binding alternative dispute resolution process that is often faster and cheaper than litigation. If negotiations with your adjuster stall and the gap is significant, the appraisal clause may be your best path forward.
The process typically works like this: you invoke the clause in writing, you and the insurer each select a competent and impartial appraiser, and the two appraisers choose a third umpire. The appraisers exchange estimates and attempt to agree on the loss amount. If they cannot agree, the umpire decides. The result is binding on both parties as to the amount of loss, though it does not resolve coverage disputes about whether the damage is covered in the first place.
Appraisal can be a powerful lever, but it is not free. You may need to pay your appraiser, and costs can run into the thousands depending on the complexity of the claim. Before invoking appraisal, weigh the cost against the potential recovery and consider whether a well-documented demand letter might persuade the insurer to increase its offer without the formality. Many insurers would rather settle than pay for appraisal, so the mere threat of invoking the clause sometimes prompts a better offer.
Document Additional Damage Found During Repairs
It is common for contractors to discover hidden damage once repairs begin. Water damage behind walls, rotted framing, or compromised electrical work can dramatically increase the cost of the job beyond what the adjuster initially estimated. When this happens, you have the right to file a supplemental claim for the additional damage, and you should do so promptly with thorough documentation.
Take photos and video of the newly discovered damage before any of it is covered up or repaired. Ask your contractor to provide a written change order or supplemental estimate that describes the additional work and its cost. Submit these materials to your adjuster with a clear cover letter explaining that the damage was not visible during the initial inspection and that you are requesting additional payment under the same claim. Insurers expect supplements on complex claims, and a well-documented supplement is usually paid without much friction.
Keep a running log of all communications with your insurer, including dates, names, and summaries of phone calls. If the supplemental claim is denied or delayed unreasonably, this log becomes valuable evidence if you later need to escalate the dispute.
Know the Bad Faith Standards and Statutory Remedies
Every state imposes a duty of good faith and fair dealing on insurers. When an insurer unreasonably delays or denies a claim, undervalues damages without a reasonable basis, or fails to investigate properly, it may be acting in bad faith. Bad faith claims can expose insurers to damages beyond the policy limit, including emotional distress, attorney fees, and in some states, punitive damages. The specific standards vary by state, so it is worth understanding the rules that apply where you live.
Signs of potential bad faith include a refusal to provide a copy of the estimate, a pattern of delaying tactics, an offer that ignores clear evidence, or a denial without a reasonable explanation. If you suspect bad faith, document everything and consider consulting an attorney who handles insurance disputes. Many insurance attorneys offer free consultations and work on contingency, so you can get an expert opinion without upfront cost.
If you are also dealing with injuries from an accident that contributed to your property damage, you may have overlapping legal needs. Resources like CarInjuryAccident connect people with attorneys who handle personal injury matters, which can be valuable if your homeowners claim is intertwined with a larger liability dispute.
Watch the Deadlines for Supplemental Claims and Appeals
Insurance policies and state laws impose deadlines that can quietly extinguish your rights. Most policies require you to submit a proof of loss within a specified period after the loss, and supplemental claims may have their own time limits. Some states allow several years to file a breach of contract lawsuit, while others impose shorter notice requirements. Missing a deadline is one of the most common ways policyholders lose leverage.
Review your policy for the suit limitation provision, which sets the deadline for filing a lawsuit against your insurer. If you are negotiating or going through appraisal, ask the insurer in writing whether it will agree to toll the deadline while the dispute is pending. Many insurers will agree to a reasonable extension, but you must ask before the deadline passes.
Keep in mind that the deadline for submitting receipts for additional living expenses or replacement cost benefits may differ from the deadline for the physical damage claim. Track each deadline separately and calendar them with reminders well in advance.
Escalate Through the Right Channels
If your adjuster is unresponsive or inflexible, escalation can help. Start with a written complaint to the adjuster's supervisor, summarizing the dispute and attaching your supporting documentation. If that does not resolve the issue, file a complaint with your state's department of insurance. Regulators track complaint patterns, and insurers often assign more experienced adjusters to claims that have been escalated to the state level.
You can also request a re-inspection of the property by a different adjuster, especially if you believe the original inspection was rushed or incomplete. A fresh set of eyes sometimes catches damage that was missed the first time. If your claim involves complex causation issues or the insurer is using technology to evaluate your claim, understanding how AI is used in insurance claim processing can help you anticipate how the insurer is analyzing your file and where human review might be warranted.
For many homeowners, the most efficient path to a fair resolution is to bring in professional help. A public adjuster or an insurance attorney can negotiate on your behalf, and their involvement often signals to the insurer that you are serious. If you are unsure whether your claim is worth fighting, a free case review can give you clarity on your options and the potential value of your dispute.
Build a Paper Trail That Supports Your Position
Throughout the process, your strongest asset is a well-organized file. Create a folder, physical or digital, that contains your policy, the adjuster's estimate, contractor bids, photos, receipts, correspondence, and notes from every phone call. When you can hand an adjuster a clean, indexed package that clearly shows the gap between the offer and the actual cost of repairs, you make it easy for them to justify a higher payment.
Write a brief cover letter or summary that walks through the dispute point by point. For example, you might explain that the adjuster estimated 20 squares of roofing at a certain price, but two local contractors confirmed 28 squares due to the pitch and complexity of the roof. Attach the bids and photos that support the higher figure. This kind of targeted, evidence-based approach is far more persuasive than a general complaint that the offer is too low.
If you ultimately hire an attorney, your organized file will save time and money. Attorneys can review your documentation quickly and identify the strongest arguments, which may increase your chances of a favorable outcome. Even if you never hire a lawyer, the discipline of building a paper trail keeps you in control of the process and protects you if the dispute escalates.
An undervalued homeowners insurance claim is frustrating, but it is rarely the final word. By comparing estimates, invoking appraisal when necessary, documenting hidden damage, understanding bad faith standards, and watching deadlines, you can push back effectively and recover the funds you are owed. The key is to act promptly, stay organized, and escalate strategically when the insurer refuses to budge.