Hospital Lien on My Car Accident Settlement: What to Do
Facing a hospital lien on your car accident settlement? Learn what to do to reduce inflated charges and protect your recovery. Call (833)-632-1198 for help.
By Thorne Bradley
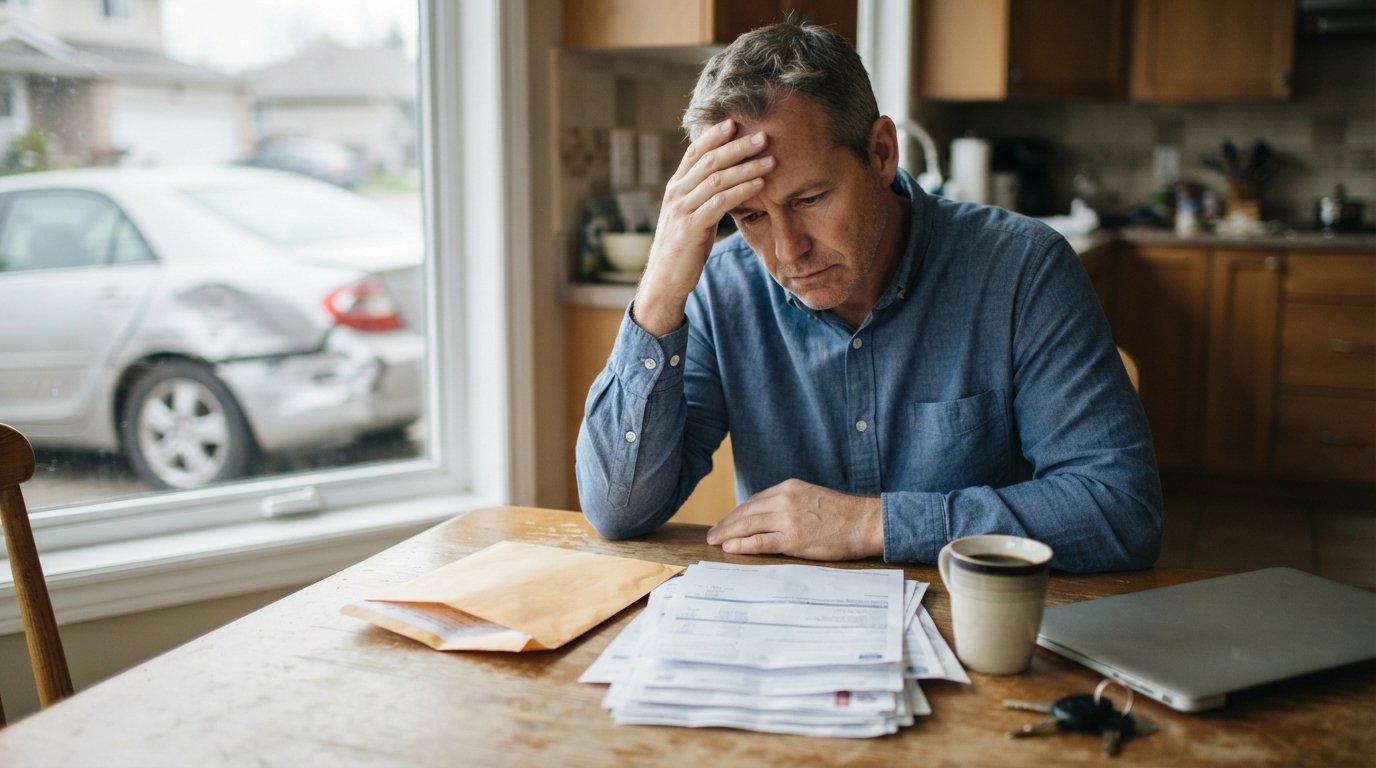
You open the mail and see it: a legal notice stating that a hospital has placed a lien on your car accident settlement. Your stomach drops. You thought your health insurance or the at-fault driver's policy would handle the bills. Now a medical provider is claiming a piece of your recovery before you even see a dime. This scenario is surprisingly common, and it can feel like a second injury. But a hospital lien is not a death sentence for your settlement. Understanding how these liens work, what rights you have, and the steps to take can protect your financial recovery.
This guide walks you through the mechanics of hospital liens, the notice requirements hospitals must follow, how to negotiate inflated charges, and how health insurance interacts with lien priority. You will also learn practical strategies to preserve as much of your settlement as possible. If you are facing a hospital lien on your car accident settlement, what to do next can shape your entire financial outcome. Let's break it down.
How Hospital Liens Attach to Your Accident Settlement
A hospital lien is a legal claim against the proceeds of your personal injury settlement or judgment. It gives the hospital a right to be paid from any money you recover from the party responsible for your injuries. The concept is rooted in statutes that allow medical providers to secure payment for emergency and ongoing care when a patient cannot pay upfront and the injuries are caused by a third party's negligence.
When you receive treatment after a car accident, you typically sign admission forms. Buried in that paperwork may be a lien agreement, or the hospital may later file a lien independently under state law. The lien attaches to any settlement, award, or insurance payout you receive from the at-fault driver or your own uninsured/underinsured motorist coverage. It does not attach to your separate health insurance benefits, but it can reach the liability portion of your recovery.
The amount of the lien is usually the hospital's billed charges, not the amount your health insurer would have paid. This distinction is critical because hospital charges are often significantly higher than negotiated insurance rates. For example, a hospital might bill $20,000 for an emergency room visit and follow-up care, while your health insurer's contracted rate might be $6,000. The lien could initially claim the full $20,000, leaving you to fight for a reduction.
Hospital liens are governed by state law, and the rules vary widely. Some states require hospitals to file a lien within a certain timeframe, notify the injured party and their attorney, and include specific information in the lien document. Others have caps on lien amounts or require hospitals to accept health insurance payments as satisfaction. Understanding your state's statute is the first step in evaluating whether a lien is valid and enforceable.
Statutory Notice Requirements Hospitals Must Follow
Hospitals do not have unlimited power to slap a lien on your settlement. Most states impose strict notice requirements. If a hospital fails to follow these rules, the lien may be invalid or unenforceable. Common requirements include:
- Filing the lien with the county clerk or appropriate government office within a specified period after treatment (often 30 to 90 days).
- Sending written notice of the lien to the injured person, their attorney (if known), and the at-fault party or their insurer.
- Including specific details in the lien, such as the date of service, the amount claimed, and the names of the parties involved.
- Providing notice before the settlement funds are disbursed, giving you and your attorney time to challenge or negotiate the lien.
If a hospital misses a deadline or omits required information, the lien may be void. This is why you should never ignore a lien notice. Instead, review it carefully with your attorney to verify compliance with state law. A defective lien can be challenged, and in some cases, the hospital may be forced to release it entirely.
Additionally, some states require hospitals to notify you of your right to contest the lien or to provide a statement of charges. Failure to do so can be a basis for reducing or invalidating the lien. Knowing these statutory requirements gives you leverage in negotiations.
Negotiating Lien Reductions for Inflated Charges
One of the most effective strategies for dealing with a hospital lien is to negotiate the amount down. Hospitals often inflate charges knowing that liens will be paid from settlement funds. However, they frequently accept less than the full billed amount, especially when you can demonstrate that the charges are unreasonable or that paying the full lien would leave you with little to no compensation for your other damages.
Here is a step-by-step framework for negotiating a lien reduction:
- Obtain an itemized bill. Request a detailed breakdown of all charges from the hospital. Review it for errors, duplicate charges, or services you did not receive. Billing errors are surprisingly common.
- Compare charges to insurance rates. If you have health insurance, find out what your insurer would have paid for the same services. This gives you a benchmark for a fair amount. Hospitals often accept the insurance rate plus a reasonable percentage.
- Highlight financial hardship. If your settlement is modest or your injuries have left you unable to work, present this evidence to the hospital. Many hospitals have charity care policies or are willing to reduce liens to avoid the cost of litigation.
- Offer a lump-sum compromise. Propose a reduced amount in exchange for full and final satisfaction of the lien. For example, if the lien is $15,000, offer $9,000 as a one-time payment. Hospitals may accept to avoid the hassle of collection.
- Get the agreement in writing. Before any funds are released, ensure the hospital provides a signed release or satisfaction of lien. This protects you from future claims.
Negotiation is often best handled by an experienced personal injury attorney who understands the hospital's billing practices and has leverage from ongoing relationships. If you are handling your own claim, be persistent and professional. Document all communications and keep copies of everything.
Another angle is to challenge the validity of the lien itself. If the hospital failed to follow statutory notice requirements, you can argue that the lien is unenforceable. Similarly, if the charges are excessive compared to community standards, you can dispute them. In some states, you can file a motion to reduce or invalidate a lien in court.
Health Insurance Reimbursement vs Hospital Lien Priority
If you have health insurance, you might wonder why a hospital lien is even necessary. The answer lies in how health insurance and liability settlements interact. Your health insurer may pay for your accident-related treatment, but it often has a right of reimbursement (subrogation) from any settlement you receive from the at-fault party. Meanwhile, the hospital may also file a lien for the portion of the bill that health insurance did not cover, such as co-pays, deductibles, or out-of-network charges.
Priority between health insurance reimbursement and hospital liens depends on state law and the specific policies involved. In many states, hospital liens are subordinate to health insurance subrogation claims, meaning the health insurer gets paid first. However, some states give hospital liens priority over other claims, including attorney fees and health insurance reimbursements. This can create a complicated web of competing interests.
Here is how the priority typically works in a car accident settlement:
- Attorney fees and costs are usually paid first (often with a lien on the settlement for fees).
- Health insurance subrogation claims may be next, depending on state law.
- Hospital liens may follow, or they may have priority depending on the statute.
- Any remaining funds go to you for pain and suffering, lost wages, and other damages.
In some states, hospitals must accept the health insurance negotiated rate as payment in full and cannot lien for the difference. This is known as a "lien on the lien" or "balance billing" protection. For example, if your health insurer pays $5,000 for a $20,000 hospital bill, the hospital may be prohibited from seeking the remaining $15,000 from your settlement. Knowing these protections can drastically reduce what you owe.
If you do not have health insurance, the hospital lien may be the primary claim against your settlement. In that case, negotiating a reduction becomes even more critical because the lien could consume a large portion of your recovery. You may also be able to apply for hospital charity care or Medicaid, which could retroactively cover some charges and eliminate the lien.
It is essential to review your health insurance policy and any correspondence from your insurer regarding subrogation. Some policies require you to cooperate with the insurer's subrogation efforts, and failing to do so could jeopardize your coverage. An attorney can help you coordinate these competing claims and ensure everyone is paid in the correct order.
Protecting Your Remaining Settlement Funds
The ultimate goal is to maximize the money you keep after all liens and fees are paid. Protecting your remaining settlement requires proactive steps before and after the lien is asserted. Here are key strategies:
1. Understand all liens before settling. Before you agree to a settlement, your attorney should identify all potential liens, including hospital liens, health insurance subrogation, and government liens (such as Medicaid or Medicare). Failing to account for a lien can result in you owing money out of pocket after the settlement is disbursed.
2. Negotiate liens aggressively. As discussed, hospital liens are often negotiable. Do not accept the first demand. Use itemized bills, insurance rates, and financial hardship arguments to reduce the amount. Your attorney can handle this negotiation on your behalf.
3. Consider a "lien resolution" service. Some attorneys specialize in resolving medical liens. They can negotiate with hospitals and insurers to reduce liens and expedite the process. If your attorney does not offer this, ask for a referral.
4. Allocate settlement funds properly. When a settlement is reached, the disbursement should clearly allocate funds to medical expenses, lost wages, pain and suffering, and other damages. This allocation can affect how liens are paid and can provide a basis for negotiating reductions. For instance, if a large portion of the settlement is for pain and suffering, you can argue that the hospital lien should be satisfied from the medical expense portion only.
5. Protect your credit. If a hospital lien is not resolved and you receive a settlement, the hospital may pursue you for the balance. Ensure that any lien is satisfied or released in writing. If you cannot pay the full lien, negotiate a release for the reduced amount. Never let a lien linger, as it could lead to collection efforts or a lawsuit.
6. Seek legal guidance early. If you are dealing with a hospital lien on your car accident settlement, what to do first is often to consult an attorney. A lawyer can review the lien for validity, negotiate on your behalf, and ensure your rights are protected. Many personal injury attorneys offer free consultations and handle lien issues as part of their representation.
Additionally, if you are searching for legal help, consider using a service like AutoInjuryAccident to request a free, confidential case review from participating attorneys. They can connect you with legal professionals who understand hospital liens and can help you navigate the process.
Finally, keep detailed records of all medical treatment, bills, lien notices, and communications. This documentation will be invaluable if a dispute arises. Being organized and informed puts you in a stronger position to protect your settlement.
Practical Steps to Take Right Now
If you have received a hospital lien notice, do not panic. Follow these steps to address it methodically:
- Contact your attorney immediately. If you are already represented, forward the lien notice to your lawyer. They will handle it according to state law.
- Verify the lien's validity. Check whether the hospital followed statutory notice requirements. Look for deadlines, proper filing, and required information.
- Request an itemized bill. Review charges for errors and compare them to insurance rates.
- Explore health insurance options. If you have health insurance, confirm whether the hospital is required to accept the negotiated rate and whether the lien is valid for any balance.
- Negotiate. Work with your attorney to negotiate a reduction. Use financial hardship and billing errors as leverage.
- Get a release. Ensure the hospital provides a written release or satisfaction of lien before funds are disbursed.
Time is of the essence. Liens can accrue interest, and delaying action may limit your options. If you are unsure about your rights, seek legal advice promptly.
For a deeper understanding of what makes a strong car accident claim, including how to document your injuries and prove liability, see this guide on key factors for a strong car accident claim. Building a robust claim from the start can put you in a better position to negotiate liens and maximize your recovery.
Remember, a hospital lien is a claim against your settlement, but it is not set in stone. With the right approach, you can reduce the amount, ensure proper priority, and keep more of the compensation you deserve. Whether you handle it yourself or with an attorney, stay proactive and informed.
If you are facing a hospital lien and need assistance finding legal representation, consider reaching out to a trusted legal information and attorney referral platform. LawyerOffer.com connects individuals with qualified attorneys who can evaluate your case and help you navigate hospital liens. Request a free, confidential case review to understand your options and protect your settlement.
Your car accident settlement is meant to help you recover and move forward. Do not let an inflated hospital lien take more than its fair share. Take action today to protect your financial future.