How to Prove Lost Earning Capacity in a Personal Injury Claim
Prove lost earning capacity with expert testimony and solid records. Call (833)-632-1198 for a free case review and maximize your settlement.
By Thorne Bradley
A serious injury can change your life in an instant, but the financial impact often unfolds slowly over years. You may recover from the immediate trauma only to realize that the career you trained for, the promotions you expected, and the retirement you planned are now out of reach. If you are pursuing a personal injury claim, understanding how to prove lost earning capacity in a personal injury claim is critical to securing the compensation you deserve. Unlike lost wages, which cover income you have already missed, lost earning capacity compensates for the diminished ability to earn in the future. Proving this requires a strategic blend of medical evidence, financial documentation, and expert testimony. This guide walks you through the process step by step, so you can build a compelling case and avoid leaving money on the table.
Lost Earning Capacity vs. Lost Wages: Key Differences
Many injury victims conflate lost wages with lost earning capacity, but they are distinct concepts in personal injury law. Lost wages refer to the income you have already lost due to time off work during recovery. These are typically straightforward to calculate: you take your salary or hourly rate and multiply it by the hours or days missed. Documentation like pay stubs and employer statements suffices. Lost earning capacity, on the other hand, is forward-looking. It represents the reduction in your ability to earn income in the future because of the injury. This includes not only the job you currently hold but also the career advancements, raises, and opportunities you might have pursued. For example, a construction worker who suffers a back injury may not only lose wages during recovery but may also be unable to return to heavy lifting, limiting his future earning potential to lower-paying sedentary work. The difference between these two categories can be substantial, and insurers often try to undervalue or deny lost earning capacity claims because they are more complex to prove. That is why you need a methodical approach to evidence gathering and expert analysis.
To effectively prove lost earning capacity, you must demonstrate that your injury has permanently or long-term diminished your ability to work and earn. This requires showing the physical or mental limitations caused by the injury, the impact of those limitations on your vocational prospects, and the financial consequences over time. Courts and insurance companies look for objective evidence, not just your testimony about pain or difficulty. In our guide on what weakens a personal injury case, we explain how gaps in evidence and inconsistent statements can undermine credibility, so it is crucial to build a seamless proof strategy from the start.
Medical Evidence: The Foundation of Your Claim
Your medical records are the cornerstone of any lost earning capacity claim. Without credible medical proof of your injury and its lasting effects, the rest of your case will crumble. Start by ensuring that all treating physicians document not only your diagnosis and treatment but also their prognosis and any permanent restrictions. Ask your doctor to include specific work restrictions in your medical records, such as lifting limits, sitting/standing limitations, or reduced hours. These restrictions directly link your injury to your inability to perform certain job tasks. Additionally, if you have pre-existing conditions, make sure the records clearly distinguish between the old injury and the new one, so the defense cannot argue that your current limitations stem from a prior issue.
Beyond immediate treatment notes, you may need expert medical testimony to establish the permanency and future impact of your injury. A treating physician or a specialist can provide a narrative report or deposition testimony explaining how your condition will affect you long-term. They can address whether you will require future surgeries, pain management, or assistive devices, all of which factor into your earning capacity. If your injury involves psychological components, such as depression or cognitive impairment, a neuropsychologist or psychiatrist can document those limitations as well. Remember that insurance adjusters are trained to look for inconsistencies, so a clear, consistent medical narrative is essential. If you are unsure where to start, consider consulting with a personal injury attorney who can guide you through the process of collecting and presenting medical evidence.
Documenting Work Restrictions and Vocational Impact
Once you have medical evidence of your limitations, the next step is to translate those limitations into vocational consequences. This is where a vocational expert often comes into play. A vocational expert is a professional who evaluates your ability to work given your injury, education, experience, and skills. They can assess whether you can return to your previous occupation, whether you need retraining, and what types of jobs (if any) you can perform. Their report will typically include a detailed analysis of your work history, the physical and mental demands of your past jobs, and the transferable skills you possess. They may also conduct labor market surveys to identify available jobs that fit your restrictions and determine the earning potential of those jobs. If no suitable jobs exist, the vocational expert can opine that you are effectively unemployable, which strengthens your claim for lost earning capacity.
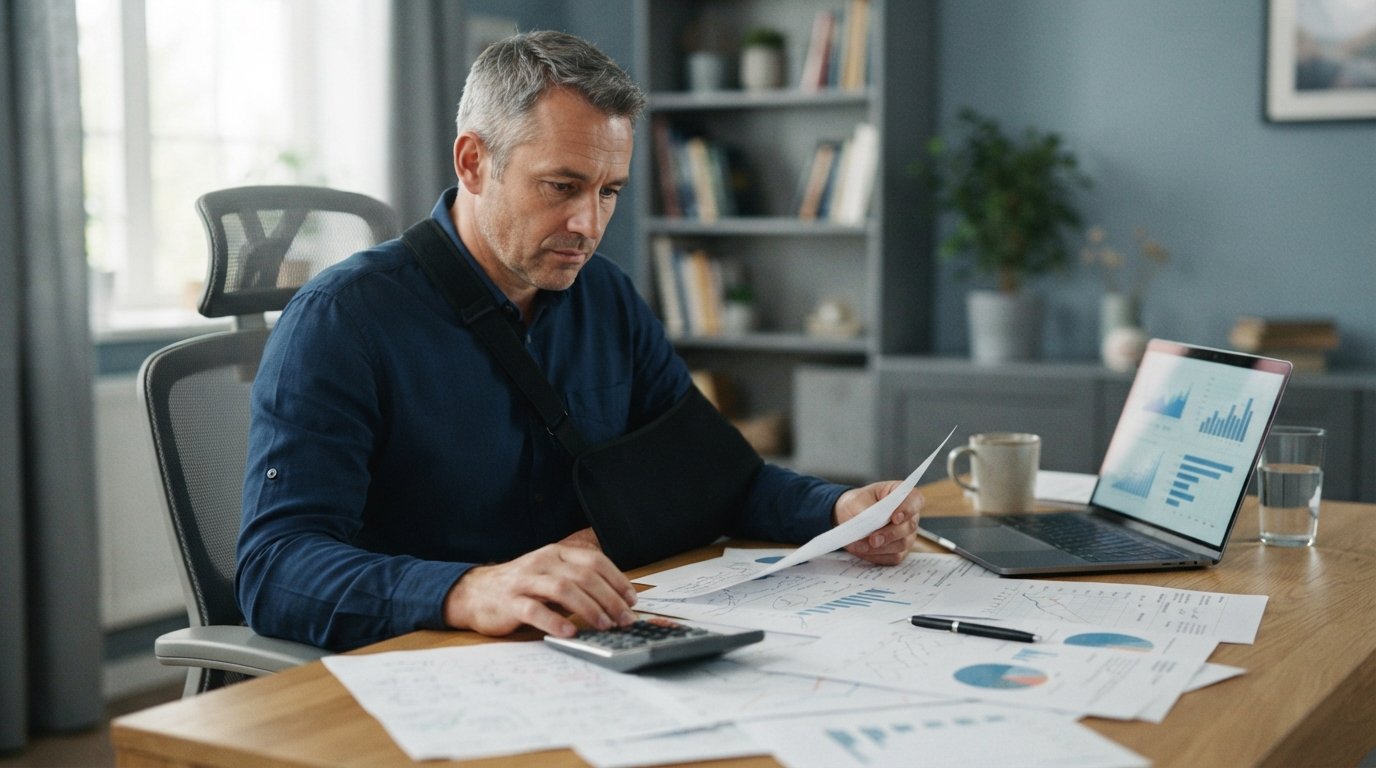
In addition to a vocational expert, you should gather evidence of your own efforts to mitigate your losses. For example, if you attempted to return to work but failed due to pain, document that. If you pursued retraining or education to transition to a new field, keep records of those efforts. Showing that you have tried to find alternative employment demonstrates good faith and makes your claim more credible. Also, obtain statements from your employer about your job duties, performance, and any accommodations they provided. If you were terminated or forced to resign because of your injury, that documentation is valuable. All of this evidence helps paint a picture of a person who is not simply claiming inability to work but has genuinely been limited by the injury.
Financial Documentation: Proving Income and Future Loss
To calculate lost earning capacity, you need to establish your pre-injury earnings and project what you would have earned but for the injury. Start by collecting financial records that reflect your income history. For salaried employees, this includes W-2 forms, pay stubs, tax returns, and employer letters verifying salary and benefits. For hourly workers, gather time sheets and pay stubs showing regular hours and overtime. If you receive bonuses, commissions, or tips, document those as well. The goal is to show a consistent pattern of earnings that can serve as a baseline for future projections. For self-employed individuals and gig workers, the documentation is more complex. You will need to provide business tax returns, profit and loss statements, invoices, client lists, and bank statements. If you work in the gig economy, such as driving for a rideshare company or delivering packages, you can use platform statements, 1099 forms, and mileage logs to prove your income. It is also helpful to get a letter from your accountant or a financial professional summarizing your income trends.
Once you have established your pre-injury income, you need to project your future earnings. This is where an economist or financial expert comes in. An economist can calculate the present value of your lost future earnings by considering factors such as your age, work-life expectancy, salary growth, benefits, and inflation. They will also account for any mitigation, such as the income you might earn in an alternative job. The economist's report will typically include a detailed calculation of economic damages, which can be used in settlement negotiations or at trial. It is important to note that lost earning capacity is not limited to your current salary; it also includes lost opportunities for promotion, raises, and career advancement. If you can show that you were on a management track or had a history of regular promotions, the economist can factor that into the projection. Similarly, if your injury prevents you from pursuing a specific career you were training for, that loss should be quantified.
Expert Testimony: Vocational Experts and Economists
Expert testimony is often the linchpin of a lost earning capacity claim. As mentioned, a vocational expert can bridge the gap between your medical restrictions and your ability to work. They can testify about the types of jobs available to someone with your limitations, the physical demands of those jobs, and the wages they pay. They can also address whether you are a candidate for retraining and how long that might take. Their testimony helps the jury or adjuster understand that your injury has real-world consequences for your employability. It is important to choose a vocational expert who has experience in your specific field or industry, as they will be more credible and persuasive.
An economist, on the other hand, focuses on the financial side. They take the vocational expert's findings and your income history and calculate the total economic loss. They can also testify about the present value of future losses, which is important because a dollar received today is worth more than a dollar received in the future. Economists use established methodologies, such as the discounted present value approach, to ensure their calculations are defensible. They may also consider fringe benefits, such as health insurance, retirement contributions, and paid time off, which are part of your overall compensation package. When presenting expert testimony, it is crucial that the experts base their opinions on reliable data and sound methodology, as the opposing side will likely challenge their conclusions. Your attorney can help you select qualified experts and prepare them for deposition and trial.
In some cases, you may also need a life care planner to quantify future medical expenses, which can indirectly affect your earning capacity. For example, if you require ongoing rehabilitation or assistive care, those costs may impact your ability to work or require you to take time off. A life care planner can create a detailed plan of future medical needs and associated costs, which can be presented alongside your lost earning capacity claim. Together, these experts provide a comprehensive picture of your damages.
Self-Employed and Gig Economy: Special Considerations
Proving lost earning capacity is particularly challenging for self-employed individuals and gig workers because income can fluctuate and may not be documented in traditional ways. If you are self-employed, you should gather as much financial evidence as possible: tax returns for at least three to five years, profit and loss statements, bank statements, credit card statements, invoices, and contracts. You may also want to obtain a letter from your CPA or bookkeeper explaining your income trends and the impact of your injury on your business. If your business relies on your personal skills or physical labor, you may need to show how your injury has reduced your ability to generate revenue. For example, a self-employed contractor who can no longer perform physical work may have to hire additional help, reducing profits. That lost profit is part of your earning capacity claim.
Gig workers, such as rideshare drivers, delivery drivers, and freelance consultants, face similar challenges. Their income is often tracked through platforms, so you should download your earnings statements and 1099 forms. Keep records of your mileage, hours worked, and customer ratings, as these can demonstrate your earning potential. If your injury prevents you from driving or performing gig work, you may need to show that you had a consistent history of earnings and that the work was your primary source of income. An economist can use this data to project future losses, but it is important to provide a clear and organized record. In all cases, consistency is key: if your reported income on tax returns is lower than what you actually earned, the defense will use that to undermine your claim. Therefore, it is wise to consult with a financial professional to ensure your documentation accurately reflects your income.
How Future Earning Losses Factor into Settlement Value
Insurance companies and defense attorneys evaluate lost earning capacity claims by looking at the evidence you present. A well-documented claim with strong medical support, vocational analysis, and economic projections will command a higher settlement value. Conversely, a claim that relies solely on your testimony or vague assertions will likely be undervalued or rejected. When negotiating a settlement, your attorney will use the expert reports to demand compensation for both past and future losses. The future loss component is often the largest part of the claim, especially for younger individuals with many working years ahead. For example, a 30-year-old injured worker with a $60,000 annual salary and a 30-year work-life expectancy could have a future loss exceeding $1 million when you factor in raises and benefits. An economist will calculate the present value of that stream of income, and that number becomes a starting point for negotiations.
It is also important to consider non-economic damages, such as pain and suffering, which can be affected by the severity of your injury and its impact on your life. While lost earning capacity is an economic damage, it often correlates with a diminished quality of life. Juries and adjusters may award higher non-economic damages when they see that your career and financial independence have been significantly impaired. Additionally, if your injury has forced you to retire early or accept a lower-paying job, that lost enjoyment of work can be factored into the overall settlement. To maximize your recovery, you should work with an attorney who understands how to present a holistic view of your damages. They can coordinate with experts, gather all necessary evidence, and negotiate with insurers from a position of strength.
If you are considering legal representation, platforms like AttorneyLeads can connect you with qualified personal injury lawyers who specialize in lost earning capacity claims. These professionals can help you navigate the complexities of proving future losses and ensure your rights are protected. Whether you are self-employed, a gig worker, or a traditional employee, having an experienced attorney on your side can make a significant difference in the outcome of your case.
Proving lost earning capacity in a personal injury claim requires a comprehensive approach that combines medical evidence, vocational analysis, financial documentation, and expert testimony. By understanding the distinction between lost wages and lost earning capacity, gathering the right records, and working with qualified experts, you can build a persuasive case that captures the full extent of your financial losses. Remember that insurance companies are not on your side; they will look for weaknesses in your claim. That is why it is essential to start documenting early, be consistent, and seek professional guidance. With the right strategy, you can secure the compensation you need to move forward with your life.