Property Damage Claim After a Car Accident: What Insurance Covers
Understand what a property damage claim covers after a crash, from repairs to total loss. Call (833)-632-1198 for a free case review.
By Barrett Quince
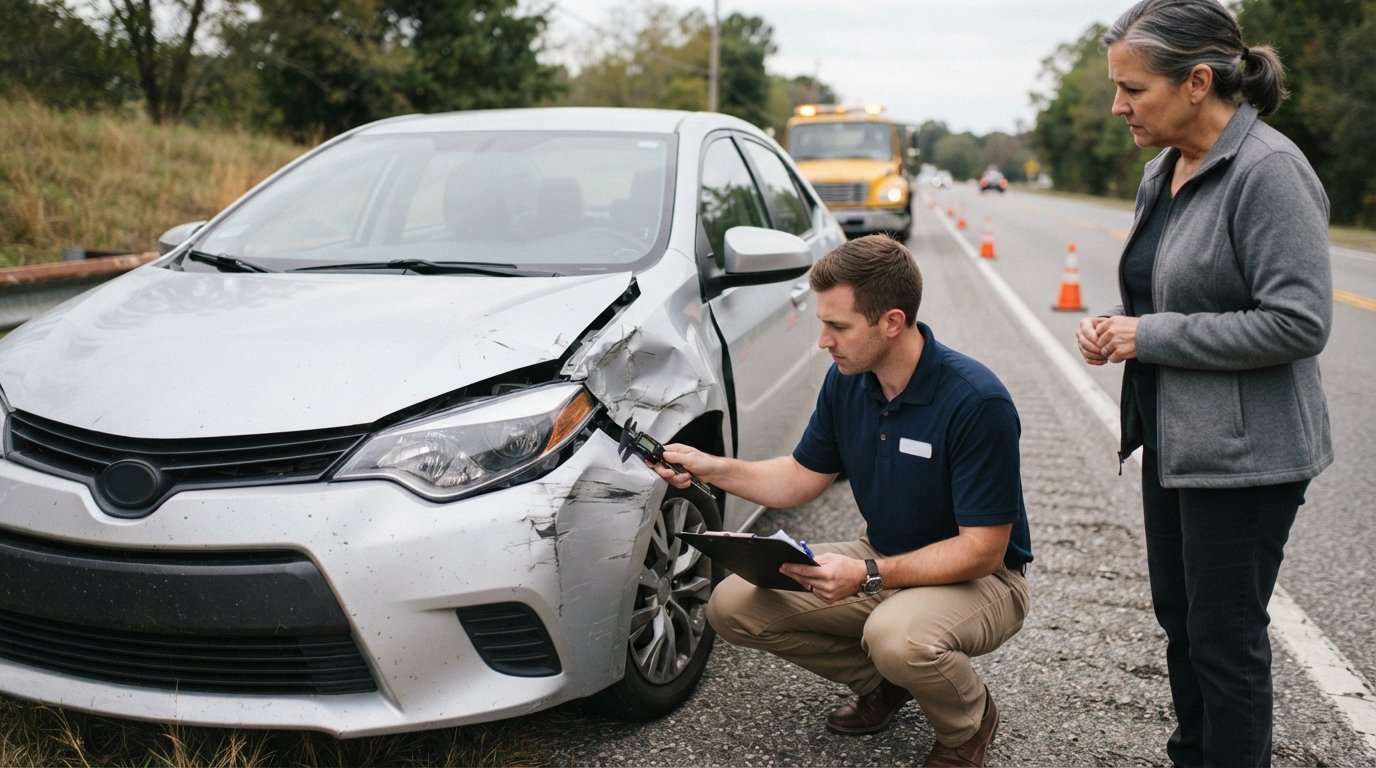
A dented fender is annoying. A crumpled frame that leaves your car undrivable is a financial and logistical crisis. In the chaotic hours after a crash, most people focus on injuries and police reports, but the damage to your vehicle is often the most immediate and tangible loss you face. Understanding exactly what a property damage claim after a car accident what insurance covers is the first step toward getting your life, and your transportation, back on track. This guide breaks down the coverage types, the claim process, and the tactics insurers use to minimize payouts, so you can protect your financial interests.
What Does Property Damage Liability Insurance Cover?
Every state except New Hampshire requires drivers to carry property damage liability coverage, though the minimum limits vary widely. This is the portion of an at-fault driver's policy that pays to repair or replace the other person's vehicle. If someone rear-ends you, their property damage liability coverage is the primary source of funds for your repairs. However, the policy only pays up to the stated limit. If the at-fault driver carries the state minimum of $10,000 and your vehicle is worth $25,000, you may face a significant shortfall unless you have your own collision coverage or uninsured motorist property damage coverage.
It is critical to distinguish between liability coverage and collision coverage. Liability pays for damage you cause to others; collision pays for damage to your own vehicle regardless of fault. If you are at fault in an accident, your own collision coverage (if you purchased it) will handle your repairs, minus your deductible. Your liability coverage will handle the other driver's repairs. Understanding this distinction is the foundation of any property damage claim after a car accident what insurance covers, because it determines which policy responds first and how the negotiation unfolds.
Repair Costs, Diminished Value, and Total Loss Valuation
When your vehicle is repairable, the insurer owes the reasonable cost of repairs to restore the vehicle to its pre-accident condition. This includes parts, labor, and paint. However, insurers often push for aftermarket parts or used parts to save money. You are generally entitled to original equipment manufacturer (OEM) parts if your vehicle is relatively new or if the policy language specifies it. Additionally, you can pursue a diminished value claim in most states. Even after perfect repairs, a vehicle with a significant accident history is worth less on the resale market. Diminished value compensates you for that lost resale value, though insurers rarely volunteer this information and often require proof through an independent appraisal.
If the repair cost exceeds a certain percentage of the vehicle's actual cash value (ACV), typically 70 to 80 percent, the insurer will declare it a total loss. In a total loss scenario, the insurer pays you the ACV of the vehicle, not the replacement cost. This is where disputes frequently arise. Insurers use valuation services like CCC or Mitchell to determine ACV, and these reports often undervalue vehicles by using generic comparables that do not account for your car's specific trim, mileage, or condition. You have the right to negotiate the ACV by providing evidence of comparable vehicles for sale in your area, recent maintenance records, and receipts for aftermarket upgrades.
How Fault and Comparative Negligence Affect Recovery
Fault determines whose insurance pays and how much you can recover. In traditional fault states, the at-fault driver's liability coverage pays for your property damage. However, most states follow some form of comparative negligence. Under pure comparative negligence, you can recover damages even if you are 99 percent at fault, but your recovery is reduced by your percentage of fault. Under modified comparative negligence, you can only recover if you are less than 50 or 51 percent at fault, depending on the state. This means that if you are partially responsible for the crash, the at-fault driver's insurer may offer a reduced settlement for your vehicle damage.
Insurers will investigate fault aggressively, looking for any reason to assign you a percentage of blame to reduce their payout. They may cite failure to yield, improper lane usage, or even contributory actions like not wearing a seatbelt (though seatbelt use generally does not affect property damage liability). This is why documenting the accident scene thoroughly is essential. If you are in a no-fault state, your own personal injury protection (PIP) or medical payments coverage handles injuries, but property damage claims still typically follow fault-based rules. The nuances of fault can complicate a property damage claim after a car accident what insurance covers, so having clear evidence of the other driver's negligence is paramount.
Rental Car Reimbursement and Loss of Use Claims
If your vehicle is in the shop for repairs, you need alternative transportation. The at-fault driver's property damage liability coverage often includes rental car reimbursement, but only for a reasonable repair period. Insurers frequently cap this at a daily rate (e.g., $30 to $50 per day) and a total maximum (e.g., $900 to $1,500). If your vehicle is a total loss, the insurer may only pay for a rental car for a few days while you find a replacement. Some policies also include loss of use, which compensates you for the inability to use your vehicle even if you do not rent a car. This is typically a daily dollar amount based on the rental value of your vehicle.
To maximize your rental reimbursement, keep the repair timeline tight. Choose a body shop that can start work immediately and communicate delays to the insurer. If the insurer delays authorization, document those delays. You may be able to claim additional rental days caused by the insurer's own red tape. If you have rental reimbursement coverage on your own policy, it may provide a backup source of funds, but the at-fault insurer remains primarily responsible. Remember that rental coverage is part of the property damage claim after a car accident what insurance covers, and it is often overlooked by claimants who are just relieved to have their car fixed.
Dealing With the At-Fault Driver's Insurer for a Total Loss
The total loss process is where insurers hold the most leverage. After declaring your car a total loss, the adjuster will make an initial offer based on their valuation report. This offer is almost always negotiable. Your job is to gather evidence that supports a higher value: listings for similar vehicles within a 100-mile radius, receipts for recent major repairs (new tires, timing belt, transmission), and documentation of any special features. You can also hire an independent appraiser, though you will pay for this upfront. If the insurer refuses to budge, many states offer an appraisal clause in the policy, which allows you to hire an appraiser and split the cost of a neutral umpire if the two appraisers cannot agree.
Another critical issue in total loss claims is the salvage value. If you retain the salvage (the damaged vehicle), the insurer will deduct its salvage value from your settlement. If you let the insurer keep the salvage, they will sell it at auction and keep the proceeds. In some cases, you may come out ahead by buying back the salvage and repairing the vehicle yourself, but this is risky if the frame is bent or the airbags deployed. Always calculate the net settlement after any liens are paid. If you have a loan or lease, the insurer pays the lienholder first, and you receive any equity. If you owe more than the car is worth, gap insurance (if you purchased it) covers the difference.
When a Property Damage Dispute May Require Legal Help
Most property damage claims settle without legal intervention. However, certain red flags suggest you need an attorney. If the insurer denies your claim outright, delays payment unreasonably, or makes a lowball offer that ignores your evidence, a lawyer can level the playing field. Disputes over diminished value, total loss valuation, or fault percentage are common areas where legal guidance pays for itself. Additionally, if the at-fault driver is uninsured or underinsured, and you have uninsured motorist property damage coverage, your own insurer may treat you like an adversary. An attorney can help you navigate the policy language and demand proper compensation.
If you are facing a complex property damage claim after a car accident what insurance covers, or if the insurer is acting in bad faith, it may be time to seek professional help. Resources like AttorneyLawsuit provide information on legal disputes involving insurers and attorneys, which can be valuable if you suspect misconduct. For a free case evaluation with a qualified attorney who handles property damage claims, consider reaching out to a service like LawyerOffer. They can connect you with legal professionals who understand the tactics insurers use and can help you maximize your recovery. Remember, the insurance company has adjusters and lawyers working for them; you deserve someone in your corner too.
Documenting the accident thoroughly from the start is your best defense against a lowball offer. In our guide on why accident reporting delays can cost you, we explain how timely reporting preserves evidence and strengthens your claim. Whether you are negotiating a repair estimate or fighting a total loss valuation, understanding your rights and the coverage available is essential. The property damage claim process is not designed to be easy, but with the right information and support, you can secure the compensation you need to get back on the road.