Uninsured Motorist Claim Denied? Steps to Take
A denied UM claim is not the end of the road. Learn why insurers deny and how to fight back. Call (833)-632-1198 for a free case review.
By Michael Turner
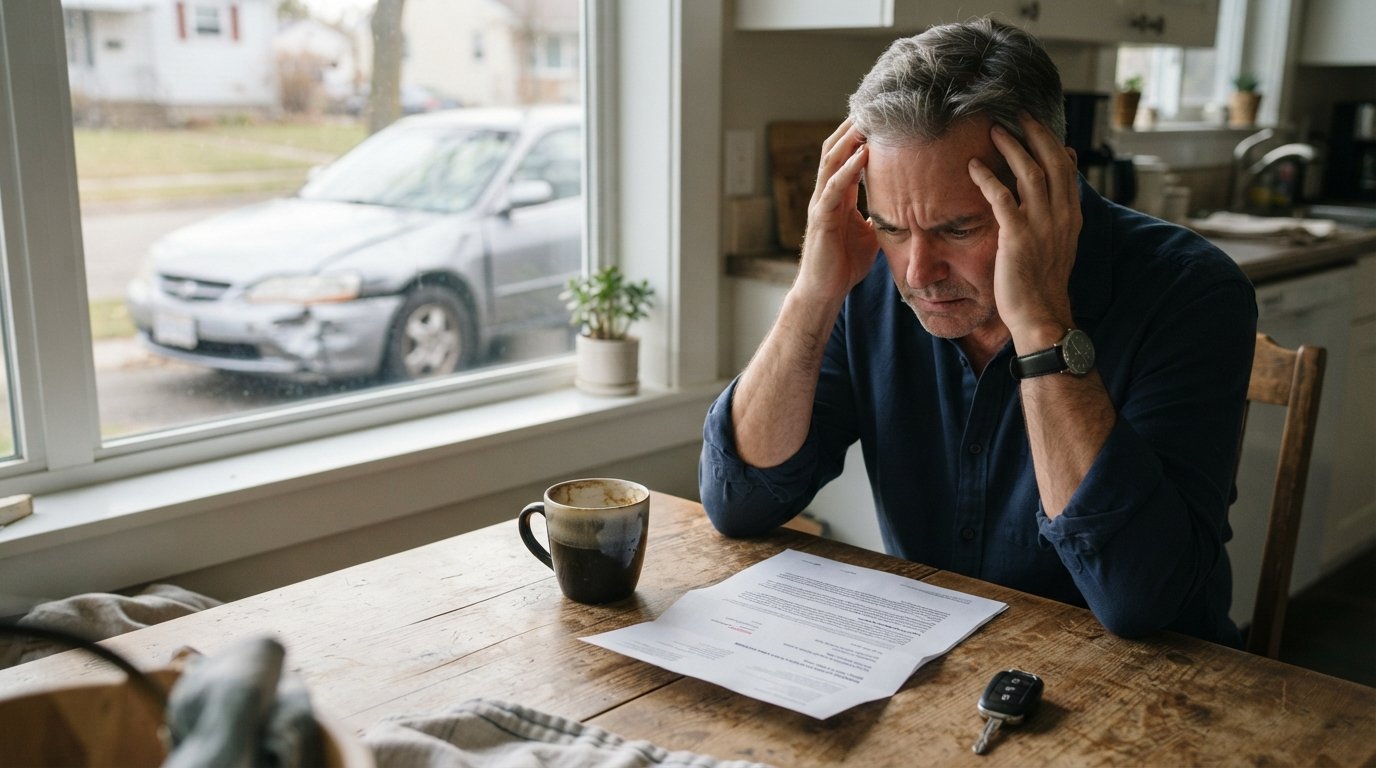
You did everything right after a crash with an uninsured driver. You filed a police report, collected what information you could, and submitted a claim to your own insurer under your uninsured motorist (UM) coverage. Then the denial letter arrived. The reasons cited may feel vague, the process opaque, and the financial exposure suddenly very real. A denied UM claim is not necessarily the end of the road, but it does mean you need to understand why the insurer said no, what proof they expect, and what leverage you have to push back.
This guide walks through the most common reasons insurers deny uninsured motorist and underinsured motorist (UIM) claims, how hit-and-run and phantom vehicle scenarios complicate eligibility, the documentation that makes or breaks a claim, bad faith remedies, and how stacking works when multiple policies are involved. The goal is practical: help you move from a denial letter toward a documented, well-supported challenge, or toward a confidential case review with a qualified attorney.
Why insurers deny uninsured motorist claims
Uninsured motorist coverage is contractual. It pays when an uninsured or hit-and-run driver is legally liable for your injuries, and the denial is almost always framed as a coverage question, a liability question, or a damages question. Insurers rarely deny UM claims outright without a stated reason, but the stated reason is often buried in policy language that policyholders never read closely. Understanding the categories of denial is the first step to challenging one.
The most frequent denial grounds fall into a handful of buckets. Review your denial letter against each of these and note which one the insurer is actually invoking, because your rebuttal strategy depends on it.
- Coverage was not purchased or was rejected in writing. Some states require insurers to offer UM coverage and to obtain a signed rejection if the policyholder declines it. If you never signed a rejection, the insurer may have a documentation problem, not you.
- The other driver was not actually uninsured. Insurers run motor vehicle records and insurance verification databases. If the other vehicle carried liability coverage, even minimal coverage, the UM claim may be recharacterized as a UIM claim or denied as premature.
- Liability is disputed. UM coverage only pays when the uninsured driver is legally liable. Comparative fault rules in your state can reduce or bar recovery if you are found partly responsible.
- Notice and cooperation failures. Late reporting, missed examinations under oath, or failure to provide requested records give insurers a contractual defense.
- Causation and damages disputes. The insurer may argue your injuries pre-existed the crash, were not caused by it, or are not supported by objective medical evidence.
Each of these grounds has a different counter. A coverage denial based on a missing rejection form is a documentary fight. A liability denial is an evidence fight. A causation denial is a medical record fight. Treat the denial letter as a roadmap and respond to the specific ground invoked rather than arguing generally that the crash was not your fault.
Hit-and-run and phantom vehicle claims
Hit-and-run crashes are where UM claims get complicated fast. The other driver is gone, so there is no insurance card to verify, no statement to obtain, and no adverse carrier to pursue. Many policies and state statutes impose special conditions for hit-and-run and phantom vehicle claims, and insurers enforce them strictly because these claims are viewed as higher fraud risk.
Typical conditions include prompt reporting to police, reporting to the insurer within a short window, and corroborating evidence that the accident involved another vehicle. Some states require "clear and convincing" evidence of a phantom vehicle's involvement, a higher bar than a typical preponderance standard. A single-vehicle crash with no witnesses and no physical evidence of a second vehicle is the scenario insurers deny most often. If you were run off the road by a vehicle that never made contact, document everything immediately: photographs of skid marks, debris, road conditions, nearby surveillance cameras, and any witnesses who saw the other vehicle.
The same documentation discipline applies to underinsured motorist claims. UIM coverage applies when the at-fault driver has insurance but not enough to cover your damages. Proving UIM eligibility requires evidence of the other driver's policy limits, which insurers often obtain through discovery or statutory disclosure. If your insurer denies a UIM claim by claiming the other driver was fully insured, demand the verification records they relied on.
Documentation that proves the other driver was uninsured
Insurers do not take your word that the other driver lacked coverage. They verify through insurance databases, police reports, and correspondence with the other driver's purported carrier. Your job is to build a record that makes denial difficult and, if litigation follows, supports your position.
Start with the police report. In most states the responding officer records insurance information for all involved drivers, and a report noting "no insurance" or "insurance not verified" is powerful evidence. Request the full report, not just the summary page, and obtain any supplement or crash reconstruction. If the other driver produced an insurance card at the scene, photograph it, note the policy number, and preserve the card if you were given a copy. An expired card or a card from a canceled policy is a common tactic, and verification will expose it.
Beyond the police report, the following records are typically needed to support a UM claim:
- Your own policy declarations page and endorsements showing UM and UIM limits, including any stacking language.
- Medical records, billing statements, and imaging that connect your injuries to the crash.
- Wage loss documentation, including employer letters and pay stubs, if you missed work.
- Photographs of vehicle damage and the accident scene, plus witness statements and contact information.
- Correspondence with the other driver's insurer, including any denial or policy limits letter.
If the other driver's insurer denies coverage or confirms a lapse, get that in writing. A written denial or a policy limits disclosure letter is the single most useful document in a UM or UIM claim. When an insurer denies a valid UM claim despite this record, the denial itself becomes evidence of bad faith.
Bad faith remedies when a valid claim is denied
Every state imposes an implied duty of good faith and fair dealing on insurers. When an insurer denies a valid UM claim without a reasonable basis, or handles the claim in a way that prioritizes its own interests over yours, policyholders may have a bad faith claim. Remedies vary by state and can include the policy benefits themselves, consequential damages, emotional distress damages, and in some jurisdictions punitive damages and attorney fees.
Bad faith is not the same as a wrong denial. Insurers are allowed to investigate, dispute liability, and rely on legitimate coverage defenses. Bad faith typically requires evidence of unreasonable conduct: ignoring evidence, failing to investigate, misrepresenting policy language, delaying payment without justification, or lowballing a clear claim. Document every communication with the adjuster, keep a claim diary, and send key requests in writing so the record shows what the insurer knew and when.
Most states also have statutory remedies specifically for UM and UIM disputes, including prompt payment acts, unfair claims settlement practices acts, and in some cases arbitration provisions built into the policy. Many UM endorsements require arbitration of coverage and damages disputes, which can be faster and less expensive than litigation but also limits discovery. Read your policy's arbitration clause carefully, and if the insurer invokes arbitration, consult an attorney before signing anything that waives rights.
If you are weighing whether to challenge a denial on your own or with counsel, resources such as how a top-rated accident attorney handles uninsured motorist claims explain how experienced counsel builds and pressures these claims. For a broader national network of attorneys who handle car crash and insurance disputes, a free, confidential case review through AutoInjuryAccident can connect you with participating lawyers who advertise on that site; coverage and deadlines vary by state, and no attorney-client relationship is formed until you sign a fee agreement.
Stacking UM coverage across multiple policies
Stacking is the practice of combining UM or UIM limits from multiple policies or multiple vehicles to increase available coverage. Whether you can stack depends on your state's law, your policy language, and the anti-stacking provisions the insurer wrote into the contract. Some states permit intra-policy stacking (combining limits for multiple vehicles on one policy), some permit inter-policy stacking (combining separate policies, such as yours and a resident relative's), and some prohibit stacking entirely or allow insurers to enforce waivers.
If you have multiple vehicles on one auto policy, check the declarations page for UM limits and any language addressing stacking. If you live with relatives who have their own policies, those policies may also provide coverage in some states. The difference can be substantial: a $25,000 UM limit stacked across three vehicles can become $75,000 in available coverage, which changes the settlement math and the insurer's willingness to deny. Stacking disputes are frequently litigated, and the outcome often turns on precise policy language and state precedent.
When a denial letter arrives, do not assume the stated coverage limit is correct. Request a certified copy of your entire policy, including endorsements and any rejection forms, and have an attorney review whether stacking, reformation, or statutory minimum coverage rules expand what is available.
Practical next steps after a denial
A denial is a decision point, not a final judgment. The policyholder who responds methodically, in writing, with documentation, is in a far stronger position than one who calls the adjuster and accepts the outcome. Treat the process like building a case file, because that is what it is.
- Request the denial in writing with the specific policy provisions cited. Insurers must usually identify the language and facts relied on. If the letter is vague, ask for clarification in writing.
- Assemble the documentation package described above, including the police report, policy declarations, medical records, and any verification of the other driver's lack of insurance.
- Submit a written dispute that addresses each denial ground directly, attaches the supporting records, and requests a supervisor review or appraisal/arbitration if the policy provides for it.
- Preserve your rights by tracking deadlines for arbitration, statutory notice, and the statute of limitations, which can be shorter than you expect.
- Get a case review if the amount in dispute is significant, the denial is weakly supported, or the insurer is stonewalling. A free consultation with a participating attorney costs nothing and clarifies your options.
If you are dealing with a denied uninsured motorist coverage claim, you can call (833)-632-1198 to discuss a free, confidential case review with participating legal professionals. The call is not legal advice, and there is no obligation to hire anyone. It is simply a way to understand whether the denial is worth challenging and what the next step should be.
Denials happen, but they are frequently reversible when the policyholder documents the file, responds in writing, and understands the coverage mechanics at issue. Start with the denial letter, build the record, and do not let a form response stand in for a decision you can appeal, arbitrate, or litigate.