What Is Subrogation and How Does It Reduce My Settlement?
Subrogation lets insurers reclaim part of your injury settlement. Understand liens and negotiation to protect your net recovery. Call (833)-632-1198 for a free case review.
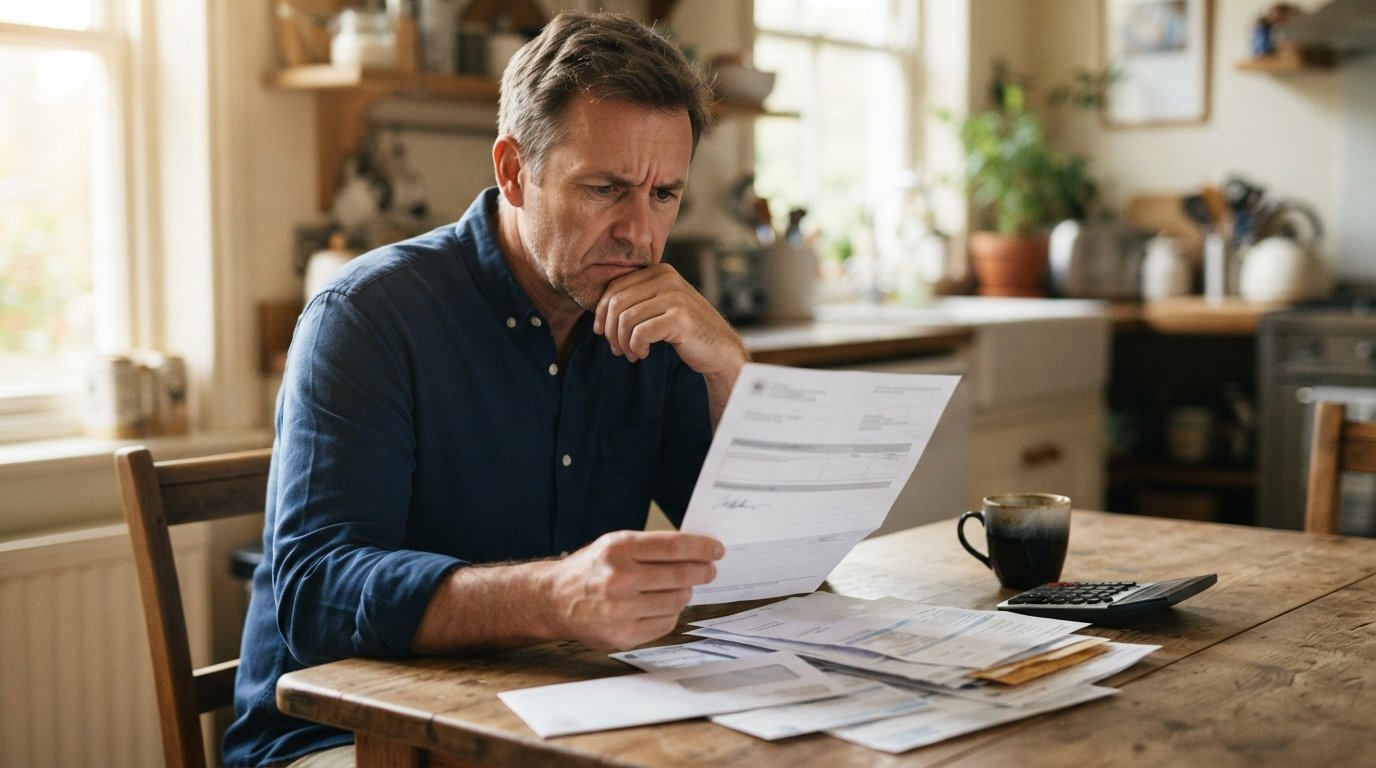
You just settled your injury claim for what felt like a fair number, and then a letter arrives from your health insurer demanding repayment for the medical bills it covered. Suddenly the money you counted on is shrinking, and you are not sure why an insurance company gets a cut of a settlement you fought for. That demand is called subrogation, and understanding it before you sign anything can mean the difference between a satisfying recovery and a frustrating shortfall.
Subrogation is a legal right that lets an insurer or government program step into your shoes to recover money it paid on your behalf after a third party caused your injury. In practical terms, it is a reimbursement claim against your settlement. The concept exists to prevent double recovery and to shift costs to the party actually at fault, but it often feels like a penalty to the injured person who already paid premiums. Knowing what is subrogation and how does it reduce my settlement starts with recognizing that your gross settlement is not your net settlement, and that liens and reimbursement rights can quietly consume a significant portion of your award.
This guide breaks down how subrogation works in practice, how health insurance subrogation differs from workers compensation liens, how Medicare and Medicaid secondary payer rules apply, how to negotiate reductions, and what to ask before you sign a reimbursement agreement. The goal is not to scare you but to give you the vocabulary and leverage to protect your recovery. If you are facing a lien demand and want a confidential review of your options, you can learn how long a personal injury settlement takes and how lien resolution fits into that timeline.
Subrogation Explained: The Legal Mechanism Behind the Reimbursement Demand
At its core, subrogation is a doctrine of equity. When an insurer pays your medical bills after an accident caused by someone else, the law allows that insurer to pursue the at-fault party for reimbursement. Rather than the insurer suing the at-fault driver directly, it asserts a claim against your settlement proceeds. You become, in effect, a temporary custodian of money that partly belongs to your insurer. The insurer's right can arise from three main sources: the language of your insurance contract, state statutes that grant subrogation rights, and common law principles. Most health plans include subrogation and reimbursement clauses in the plan documents, and courts generally enforce them.
The practical effect is that your personal injury attorney must resolve these claims before distributing money to you. A well-drafted demand letter and settlement agreement often include language about liens, and the settlement check may be made payable to both you and your insurer or your attorney's trust account. If liens are ignored, the insurer can pursue you personally after the settlement, sometimes even years later. That is why experienced attorneys treat lien resolution as a core part of the case rather than an afterthought.
There is an important distinction between subrogation and reimbursement. Subrogation technically means the insurer steps into your legal shoes and pursues the at-fault party. Reimbursement means the insurer has a right to be paid back from your recovery. Many plan documents use the terms interchangeably, and in practice both reduce your net settlement. The key takeaway is that a subrogation or reimbursement claim is not optional courtesy; it is a legal entitlement that must be addressed.
Several factors determine how much an insurer can actually recover. These include whether the insurer was fully or only partially responsible for the medical payments, whether the settlement expressly allocated money for medical expenses versus pain and suffering, whether the made-whole doctrine applies in your state, and whether common fund rules require the insurer to share in attorney fees and costs. Understanding these levers is where negotiation begins.
Health Insurance Subrogation Versus Workers Compensation Liens
Health insurance subrogation and workers compensation liens are often lumped together, but they operate under different rules and different leverage points. Health insurance subrogation typically arises from a private plan, an employer-sponsored plan governed by ERISA, or an individual policy. The insurer paid medical bills related to an accident caused by a third party, and it now seeks reimbursement from your liability settlement. Workers compensation, by contrast, is a no-fault system in which the employer or its carrier pays medical and wage benefits regardless of fault. When a third party also caused the injury, the workers compensation carrier has a statutory lien against the third-party recovery.
The differences matter for negotiation. Workers compensation liens are often governed by state statutes that set formulas for how much the carrier can recover, whether it must contribute to attorney fees, and whether the injured worker must be made whole first. Some states apply a statutory percentage reduction to the lien to account for the worker's attorney fees and costs. Health insurance subrogation, especially under ERISA plans, is often more aggressive because federal law can preempt state insurance regulations that would otherwise limit reimbursement. That means an ERISA plan may demand full reimbursement even when the injured person's recovery is modest.
Here is a quick comparison of the key differences:
- Governing law: Health plans are often governed by ERISA or state insurance codes, while workers compensation liens are governed by state workers compensation statutes.
- Fault requirement: Health subrogation requires a third party at fault, while workers compensation pays regardless of fault and then seeks reimbursement from the third party.
- Made-whole rules: Many states apply made-whole protections to workers compensation liens, but ERISA plans frequently argue those protections are preempted.
- Attorney fee sharing: Workers compensation statutes often require the carrier to contribute to the injured worker's attorney fees, while health plans may resist common fund contributions.
Because these rules vary so much by state and by plan type, the same settlement number can produce very different net results depending on which type of lien is involved. If you are unsure which category your lien falls into, request the plan documents and the lien notice in writing. The documents will reveal whether the claim is asserted under ERISA, state law, or a workers compensation statute, and that determines your negotiating strategy.
Medicare and Medicaid Secondary Payer Rules in Injury Settlements
Medicare and Medicaid add another layer of complexity because they are government payers with statutory reimbursement rights. Under the Medicare Secondary Payer Act, Medicare is generally prohibited from paying for medical care when another payer, such as a liability insurer, is responsible. When Medicare does pay conditionally and a settlement later occurs, Medicare has a right to recover those conditional payments. This is why personal injury attorneys routinely check for Medicare liens before distributing settlement funds.
Medicare lien resolution can be time-consuming. The Centers for Medicare and Medicaid Services maintains a process for obtaining a final demand amount, and the amount can change as claims are processed. Attorneys often request a conditional payment letter early and then a final demand before disbursement. If the settlement includes future medical care that Medicare would otherwise cover, the parties may need to address Medicare's interests through a Medicare Set-Aside arrangement or documented consideration of future medical expenses. Failing to protect Medicare's interests can expose the parties to later claims.
Medicaid operates differently because it is a joint federal-state program, and state Medicaid agencies often assert liens under state law. Some states have statutory formulas that reduce the lien, and some apply the made-whole doctrine. Medicaid liens can sometimes be negotiated more flexibly than Medicare demands, but the rules vary widely. The practical lesson is that any settlement involving a Medicare or Medicaid beneficiary requires early identification of the lien, documentation of the payments, and a plan for resolution before funds are released.
For readers who want to understand how these timelines play out in practice, the interplay between lien resolution and disbursement is one reason settlement timing can stretch. A confidential case review can help clarify which liens apply to your situation and what steps are needed to resolve them.
Negotiating Lien Reductions With Providers and Carriers
Many injured people assume a lien demand is final. It is not. Lien reduction negotiation is a standard part of personal injury practice, and there are several legitimate arguments for reducing the amount an insurer or provider claims. The strength of these arguments depends on your state's law, the type of plan, and the specific language in the plan documents or statutes.
One of the most powerful arguments is the made-whole doctrine. In states that recognize it, an insurer cannot recover from a settlement unless the injured person has been fully compensated for all damages, including pain and suffering, future medical care, and lost earning capacity. If your settlement is modest relative to your total damages, the made-whole argument can eliminate or sharply reduce the lien. Another argument is the common fund doctrine, which requires an insurer that benefits from your attorney's work to contribute to the attorney fees and costs you incurred to obtain the settlement. Many courts hold that a subrogated insurer must share in those costs proportionally.
Additional negotiation levers include:
- Procurement costs: Ask the carrier to reduce the lien by a percentage representing your attorney fees and case expenses.
- Disputed charges: Audit the lien for payments unrelated to the accident, duplicate charges, or amounts already adjusted by providers.
- Future medical allocation: If part of the settlement is for future care, argue that the lien should not be satisfied from funds intended for care the insurer will not cover.
- Statutory caps and formulas: Some states impose formulas that limit recovery or require the carrier to bear a share of fees.
- Hardship and policy arguments: In some cases, carriers will reduce liens to avoid litigation or because the injured person's recovery is disproportionately low.
Negotiation works best when it is documented and professional. Send a written request that identifies the legal basis for reduction, attaches supporting evidence such as the settlement breakdown and attorney fee agreement, and proposes a specific reduced amount. Carriers respond better to clear, reasoned positions than to emotional appeals. If the carrier refuses to negotiate, your attorney may need to consider declaratory judgment actions or interpleader, though those steps are costly and usually reserved for significant disputes.
It also helps to understand the carrier's perspective. Insurers have internal recovery targets and often accept reasonable reductions to close files efficiently. A well-supported request that saves the carrier time and litigation risk can succeed even when a bare demand would fail.
Why the Collateral Source Rule Varies by State
The collateral source rule is a legal principle that prevents a defendant from reducing its liability by pointing to payments the injured person received from other sources, such as health insurance, disability insurance, or workers compensation. In states that follow the rule, the jury may award full damages for medical expenses even if the plaintiff's insurer paid a discounted rate, and the defendant cannot introduce evidence of those collateral payments to reduce the award. The rationale is that the plaintiff paid for the insurance and should receive the benefit of the bargain.
However, the collateral source rule is not uniform. Some states have modified or abolished the rule in certain contexts, allowing defendants to introduce evidence of collateral payments or requiring post-verdict reductions. In medical malpractice cases, many states have statutory collateral source offsets. The variation matters for settlement valuation because it affects how much a defendant is willing to pay and how much of that payment is exposed to subrogation. In a state with a strong collateral source rule, the plaintiff may recover more for medical expenses, but the insurer's subrogation claim may also be larger. In a state with a weakened rule, the recovery may be lower, but the lien may be smaller or subject to offset.
For settlement purposes, the practical question is how the parties allocate the settlement. If the settlement agreement expressly allocates a portion to medical expenses and a portion to pain and suffering, that allocation can affect the subrogation claim. Insurers often argue that they are entitled to reimbursement from the medical expense portion, while plaintiffs argue that the made-whole doctrine or common fund principles limit recovery. Courts in different states treat these allocation disputes differently, and some require that the allocation be made in good faith and reflect the actual damages.
Because the rules vary so much, a settlement strategy that works in one state may fail in another. Injured people should ask their attorney how the collateral source rule and subrogation statutes interact in their jurisdiction. If you are evaluating a potential claim and want to understand how local rules affect your net recovery, you can request a free, confidential case review from participating attorneys who practice in your state. For nationwide resources on accident claims and fault rules, AutoInjuryAccident provides helpful consumer information for people injured in car crashes and related incidents.
Questions to Ask Before Signing a Reimbursement Agreement
Before you sign any reimbursement agreement, release, or lien resolution document, ask questions that clarify exactly what you are giving up and what you are preserving. A reimbursement agreement may include language that waives future claims, admits liability, or grants the insurer rights beyond what the law requires. You want to know the final number, the legal basis for the claim, and whether the agreement affects your ability to recover other damages.
Here are the key questions to ask:
- What is the exact amount claimed, and how was it calculated? Request an itemized statement and verify that every charge relates to the accident.
- What legal authority supports the lien? Ask whether the claim arises from a contract, a statute, or common law, and whether ERISA or state law governs.
- Does the made-whole doctrine apply in my state, and have you applied it? If your recovery is less than your total damages, this argument may reduce or eliminate the lien.
- Will the carrier contribute to my attorney fees and costs? Ask about common fund or procurement cost reductions.
- Does this agreement waive any of my rights? Look for language about future claims, confidentiality, or admissions.
- What happens if I do not sign? Understand the carrier's options and whether litigation is likely.
The answers should be in writing whenever possible. Verbal assurances are difficult to enforce, and a written record protects you if a dispute arises later. If the carrier will not provide a written explanation, that is a red flag. You should also confirm that the agreement resolves the lien fully and that no balance will be pursued against you personally.
It is also wise to ask whether the agreement affects Medicare or Medicaid interests. If you are a beneficiary, the reimbursement agreement should be coordinated with any Medicare Set-Aside or Medicaid lien resolution. Signing a private reimbursement agreement without addressing government payer interests can create problems later.
Practical Steps to Protect Your Net Settlement
Protecting your net settlement begins before you sign a settlement release. The first step is to identify all potential liens early. Ask your attorney to send written notices to your health insurer, Medicare, Medicaid, and any workers compensation carrier. Early notice gives you time to obtain conditional payment information and to negotiate before funds are disbursed.
The second step is to document everything. Keep copies of medical bills, explanation of benefits statements, lien notices, and correspondence with carriers. If a carrier claims an amount that seems inflated, you can audit the charges and dispute unrelated payments. Documentation also supports arguments for reduction based on procurement costs and made-whole principles.
The third step is to negotiate before the settlement is finalized when possible. Some attorneys negotiate lien reductions as part of the overall settlement strategy, using the threat of litigation or the uncertainty of recovery as leverage. Others wait until the settlement is funded, which can weaken the plaintiff's position because the carrier knows the money is available. The timing depends on the case and the carrier's willingness to engage.
Finally, consider the tax consequences. Settlement proceeds allocated to medical expenses may be excluded from income, but the subrogation reimbursement itself is not a deductible expense. The interaction between tax rules and lien resolution can be complex, and you should consult a tax professional if the amounts are significant.
If you are facing a lien demand and want help understanding your options, a confidential case evaluation can connect you with attorneys who handle subrogation and lien resolution in your state. The goal is to preserve as much of your recovery as possible while satisfying valid claims and avoiding future liability.
Subrogation does not have to erase the value of your settlement. With early identification, informed negotiation, and a clear understanding of the rules that apply in your state, you can reduce the amount that comes out of your recovery and keep more of what you fought for. The key is to treat lien resolution as part of the case from the beginning, not as a surprise at the end.