How Insurers Use AI to Evaluate Injury Claims
Insurers use AI to score claims and flag fraud, but documented medical evidence can still win. Call (833)-632-1198 for a free case review.
You file an injury claim after a car crash, expecting a fair review of your medical bills and lost wages. Weeks later, a settlement offer arrives that feels disconnected from your actual suffering. You wonder if a human ever looked at your file. In many cases, the answer is no, or at least not first. Insurance companies increasingly deploy artificial intelligence to evaluate injury claims, using algorithms to score severity, flag fraud, and predict what a case might be worth. Understanding how these systems work is the first step toward protecting your recovery.
The Rise of Automated Claims Triage
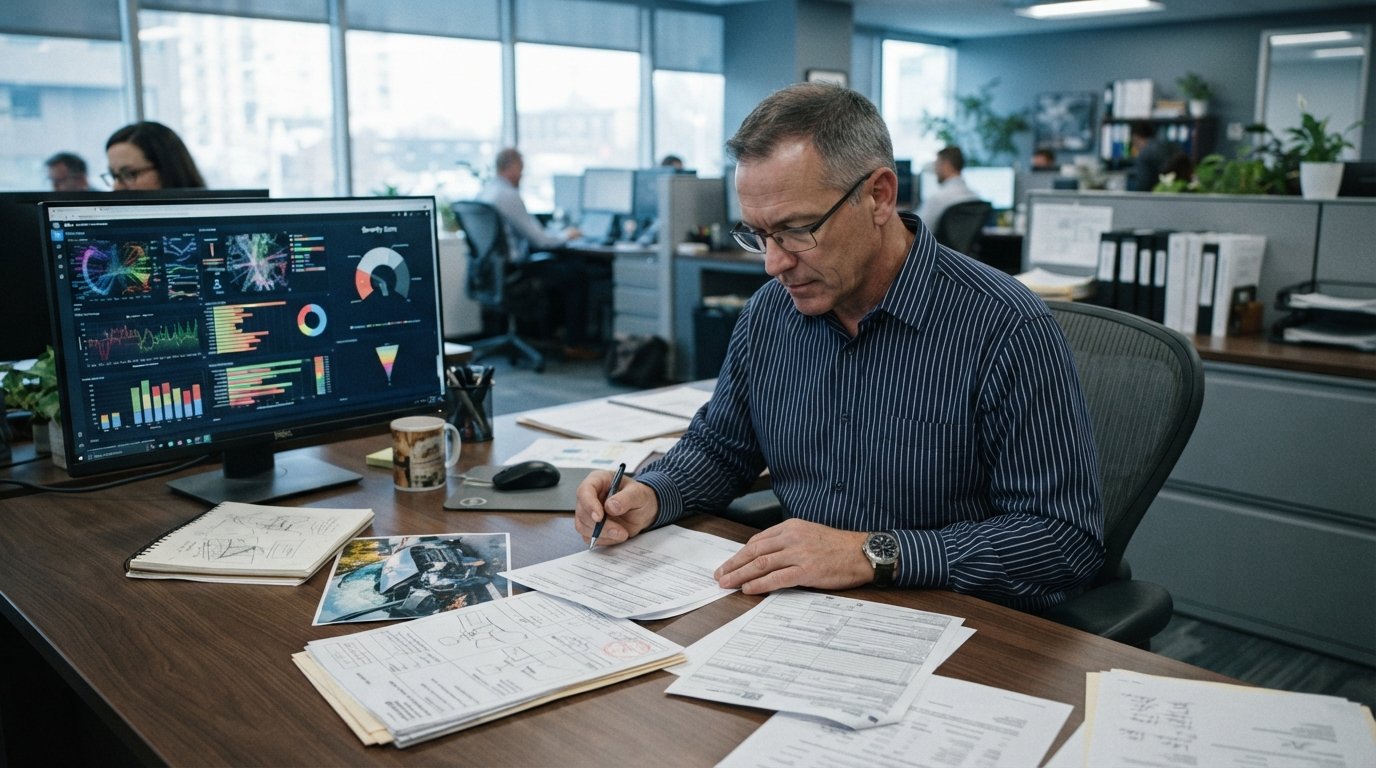
Insurance carriers have invested heavily in claims automation over the past decade. The goal is efficiency: processing thousands of claims quickly, identifying high-risk files, and setting reserves. When you submit a personal injury claim, software may immediately extract data from your medical records, police reports, and correspondence. Natural language processing tools scan for keywords like "surgery," "fracture," or "chiropractor" and assign a severity score. Machine learning models then compare your claim to historical settlements with similar characteristics to generate a recommended payout range.
This triage process does not replace adjusters entirely, but it shapes the conversation. A low algorithmic score can lead an adjuster to offer a minimal amount, while a high score might trigger a more generous initial offer (or a referral to legal counsel for the insurer). The opacity of these systems is a major concern for injured people who cannot see why their claim was valued the way it was.
How Insurers Deploy AI to Flag and Score Claims
Insurers use AI at multiple stages of the claims lifecycle. Early on, predictive models assess the likelihood that a claim is fraudulent or exaggerated. These models analyze patterns in the claim data: the time between the accident and the first medical visit, the number of providers seen, the type of treatment, and even the wording of the demand letter. A claim that deviates from the norm may be flagged for special investigation, leading to delays and requests for additional documentation.
For valuation, insurers employ injury severity models that categorize claims into tiers. These models are trained on millions of closed claims, learning which combinations of injuries, treatments, and demographics correlate with certain settlement amounts. The output is not a final offer but a data point that guides the adjuster. If your claim involves soft tissue injuries with minimal treatment, the model may predict a low value. If you have documented fractures, surgeries, or ongoing physical therapy, the predicted value rises.
Another common use is optical character recognition (OCR) combined with AI to digitize medical records and bills. The system extracts procedure codes, diagnoses, and billing amounts, then cross-references them against fee schedules and historical data to identify overbilling or inconsistencies. This can speed up payments for legitimate claims, but it can also lead to automated denials if the extracted data does not match the insurer's expectations.
Common Patterns in Algorithmic Denials and Lowball Offers
When AI evaluates injury claims, certain patterns emerge that injured people should recognize. One frequent pattern is the "treatment gap" flag: if there is a lull in medical treatment, the algorithm may interpret it as evidence that the injury was not serious. In reality, many people skip appointments due to cost, transportation issues, or feeling better before a setback. Another pattern is the "excessive treatment" flag: seeing multiple specialists or undergoing extensive diagnostic testing can trigger suspicion of malingering, even when medically necessary.
Lowball offers often result from models that undervalue pain and suffering, future medical needs, or lost earning capacity. These intangible damages are harder to quantify, so algorithms may rely on limited proxies such as the number of days missed from work or the total of medical bills. If your claim involves significant noneconomic damages, an automated valuation may fall far short of a fair settlement.
Denials can also be automated. If the AI detects a pre-existing condition or a prior claim for the same body part, it may recommend denial or a reduced payout. While insurers are legally required to consider the proximate cause of injury, the algorithm may not weigh the nuances of aggravation of a pre-existing condition. This is where human review and legal advocacy become critical.
Why Documented Medical Evidence Still Outweighs Models
Despite advances in AI, the foundation of any injury claim remains solid medical evidence. Insurance algorithms are only as good as the data they receive. If your medical records clearly document the mechanism of injury, objective findings (such as MRI results or X-rays), and a consistent treatment plan, the AI is more likely to assign a higher severity score. Conversely, gaps in documentation or vague complaints can lead to lower valuations.
Personal injury attorneys understand this dynamic. They work with medical providers to ensure records are complete and compelling. They also know that AI models often fail to capture the full impact of an injury on a person's life, such as chronic pain, emotional distress, or inability to perform daily activities. By building a strong evidentiary record, you can counter the limitations of automated tools. For example, in cases involving psychological injuries like PTSD, the nuances of diagnosis and treatment are often poorly captured by algorithms, making expert documentation essential. Our guide on how PTSD claims are evaluated in accident cases explains how to present this evidence effectively.
Steps to Challenge an Automated Valuation
If you believe an AI-driven system has undervalued your claim, you have options. The first step is to request a detailed explanation of the valuation. While insurers may not reveal proprietary algorithms, they can provide the data points used, such as medical bill totals, treatment dates, and any flags. Review this information for errors, such as missing records or incorrect injury codes.
Next, gather additional evidence to strengthen your file. This can include:
- Letters from treating physicians explaining the severity of your injury and its impact on your life.
- Records of ongoing treatment or future medical recommendations.
- Documentation of lost wages or reduced earning capacity.
- Witness statements or accident reconstruction reports that clarify liability.
With this evidence, you can submit a formal demand letter that directly addresses the weaknesses in the automated evaluation. Point out any inconsistencies or oversights in the insurer's data. If the adjuster remains inflexible, you may need to escalate the dispute. Many states offer mediation or appraisal processes for insurance claims. In some cases, filing a complaint with the state insurance department can prompt a more thorough review.
It is also wise to consult with an attorney who understands how insurers use AI. Attorneys can use discovery tools to uncover how a claim was evaluated and challenge improper reliance on algorithms. They can also negotiate directly with senior adjusters or file a lawsuit if necessary, which often leads to a more human review of the claim.
When to Bring in an Attorney to Counter Insurer Analytics
Not every claim requires legal representation, but certain red flags suggest you should seek help. If your claim is denied outright or you receive an offer that seems far below your medical expenses, an attorney can investigate whether an algorithm improperly influenced the decision. If you have complex injuries, multiple parties involved, or a dispute over fault, the stakes are higher and insurers are more likely to deploy sophisticated analytics to minimize payouts.
Attorneys can level the playing field by conducting their own analysis and presenting a compelling case that goes beyond what an algorithm can capture. They also understand the tactics insurers use to delay and devalue claims, and they can push back effectively. If you are facing a serious injury and want to ensure your claim is evaluated fairly, consider reaching out to a legal professional. For those in need of guidance on finding representation, CarInjuryAccident offers a platform to connect with seasoned attorneys specializing in personal injury and other civil matters.
The Future of AI in Injury Claims and What It Means for You
As AI tools become more sophisticated, insurers will likely rely on them even more. However, regulators and courts are paying closer attention to the use of algorithms in claims handling. Some states have proposed rules requiring transparency and human oversight. The outcome of these debates will shape how much power algorithms have over your settlement.
For now, the best defense is a well-documented claim and, when necessary, legal representation. Understanding the basics of how AI evaluates injury claims empowers you to ask the right questions and challenge unfair offers. Remember that behind every algorithm is a human decision-maker, and you have the right to advocate for a fair outcome. If you are unsure where to start, consider a free case review with a qualified attorney to assess your options. Do not let an automated score determine the value of your injury.