Total Loss Car Accident Claim Payout: How Is Value Calculated?
Total loss car accident claim payout how is value calculated? Get clarity on ACV, negotiation, and more. Call (833)-632-1198 for a free case review.
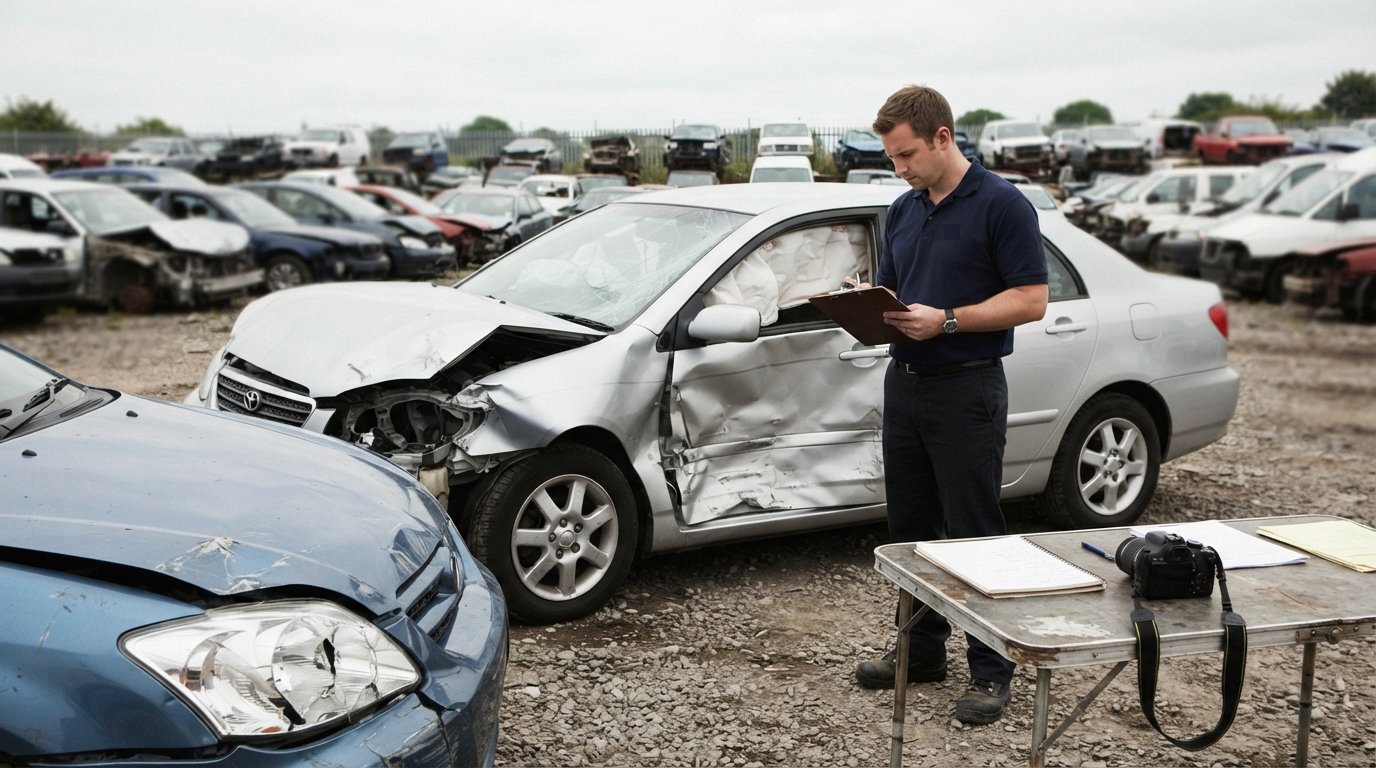
When your car is declared a total loss after an accident, the payout you receive from the insurance company is based on the vehicle's actual cash value (ACV), not on what you originally paid or what it would cost to buy a replacement. Understanding how that value is calculated is critical because it directly determines how much money you get to settle your claim. Insurers use specific methods to determine ACV, and those methods can sometimes undervalue your car. This guide explains the calculation process, the difference between ACV and replacement cost, how to negotiate a higher offer, and what to do about gap insurance, taxes, fees, and rental reimbursement.
Actual Cash Value vs. Replacement Cost: What's the Difference?
Actual cash value (ACV) is the fair market value of your vehicle just before the accident, minus depreciation. It reflects what you could have sold the car for in its pre-accident condition. Replacement cost, on the other hand, is the amount it would take to buy a comparable vehicle today, without deducting for depreciation. Most standard auto insurance policies pay ACV for total losses, not replacement cost. That means if your car was worth $15,000 before the accident, you will not receive $20,000 to buy a newer model. The gap between ACV and replacement cost can be significant, especially for newer cars that depreciate quickly.
Some insurers offer replacement cost coverage as an add-on, but it is not standard. If you have this coverage, the payout may be closer to what you need to actually replace the vehicle. Always check your policy declarations page to see which valuation method applies. Knowing this upfront helps you set realistic expectations and plan your next steps.
How Insurers Calculate Actual Cash Value
Insurance companies typically use one of several methods to determine ACV: the market comparison approach, the cost approach, or the income approach (rarely used for cars). The most common is the market comparison approach, which looks at recent sales of comparable vehicles in your area. The insurer will gather data from sources like Kelley Blue Book, NADA Guides, and local dealer listings. They adjust for mileage, condition, options, and aftermarket additions. The result is a valuation report that shows the base value and any adjustments.
However, these reports are not always accurate. They may miss certain features, use outdated data, or apply generic condition ratings that do not reflect your car's actual state. For example, if you recently installed a new transmission or upgraded the sound system, those additions may not be fully accounted for. That is why it is essential to review the valuation report carefully and provide documentation for any upgrades or recent maintenance that could increase value.
Here are the key factors insurers consider when calculating ACV:
- Year, make, model, and trim level: The base value is determined by these characteristics.
- Mileage: Higher mileage reduces value; lower mileage increases it.
- Condition: Overall wear and tear, including interior and exterior damage not related to the accident.
- Options and packages: Features like leather seats, sunroof, navigation, and advanced safety systems add value.
- Aftermarket additions: Upgraded wheels, audio systems, or performance parts may add value if documented.
- Location: Regional market demand can affect value.
Each of these factors is assigned a dollar amount or percentage adjustment. The insurer then adds or subtracts from the base value to arrive at the final ACV. If you disagree with any adjustment, you can challenge it with evidence.
Valuation Reports, Comparables, and Add-On Equipment
When you receive a total loss settlement offer, the insurer should provide a valuation report that details how they arrived at the number. This report typically includes a list of comparable vehicles (comps) that were recently sold or listed for sale in your area. You have the right to review these comps and verify that they truly match your car's make, model, year, mileage, and condition. Sometimes insurers use comps from different regions or with different options, which can skew the value downward.
Add-on equipment is another area where valuations often fall short. If you added a bed liner, roof rack, or premium sound system, those items may not be included in the base value. To get credit, you need to provide receipts or other proof of purchase. The same goes for recent major repairs, like a new engine or transmission, which can increase the car's value. Without documentation, the insurer has no reason to adjust the offer.
If you believe the valuation is too low, you can request a copy of the report and compare it to your own research. Use online tools like Kelley Blue Book, Edmunds, or local classified ads to find comparable listings. If you find discrepancies, present them to the adjuster with a clear explanation. In many cases, insurers will revise the offer if you provide solid evidence.
Negotiating a Total Loss Offer Upward
Negotiating a total loss settlement is not only possible but often necessary. The first offer is rarely the final offer. To start, gather all relevant documents: maintenance records, receipts for upgrades, and listings for comparable vehicles. Then, contact the adjuster and politely explain why you think the valuation is incorrect. Be specific: point out missing options, undervalued condition, or comps that do not match. If the adjuster is unresponsive, escalate to a supervisor.
It also helps to understand the insurer's perspective. They are motivated to settle quickly and for as little as possible, but they also want to avoid complaints to state insurance regulators. If you present a well-reasoned case, they may increase the offer to avoid a dispute. In some states, you have the right to invoke an appraisal clause, which brings in an independent appraiser to determine the value. This can be a powerful tool if negotiations stall.
For a deeper look at how accident claims are evolving and what that means for your payout, see our guide on how modern accident claims differ in 2026. It covers recent changes that could affect your total loss valuation.
Gap Insurance and Loan Balance Shortfalls
If you have a loan or lease on your car, the ACV payout may be less than what you owe. This is known as being "upside down" on your loan. Gap insurance covers the difference between the ACV and the remaining loan balance, up to policy limits. Without gap insurance, you would be responsible for paying off the shortfall out of pocket. Many new car buyers purchase gap insurance, but it is not automatically included in all policies.
If you do not have gap insurance, you may still be able to negotiate with your lender. Some lenders offer payment plans or deferments for the remaining balance. It is also worth checking whether your auto insurance policy includes any coverage for loan/lease payoff, which is similar to gap insurance but may have different terms. Review your policy carefully and ask your adjuster if you are unsure.
Sales Tax, Fees, and Rental Reimbursement After a Total Loss
When your car is totaled, the settlement should include more than just the vehicle's value. In many states, insurers are required to pay sales tax on the replacement vehicle, as well as title and registration fees. These costs can add hundreds or thousands of dollars to your settlement. Do not accept an offer that omits them. Check your state's insurance regulations to confirm what is required.
Rental reimbursement is another important component. If you have rental reimbursement coverage, your insurer will pay for a rental car while your claim is being processed, up to your policy limits. Even without this coverage, some insurers provide a rental as a courtesy. Be sure to ask about the duration and daily limit. Keep receipts for any out-of-pocket rental expenses, as you may be able to include them in your claim.
If you are facing a total loss and need legal guidance, consider reaching out to a legal professional. Platforms like AttorneyLawsuit offer resources and information about attorney-related lawsuits and consumer rights, which can be helpful if you encounter disputes with your insurer or lender.
Steps to Take If You Disagree with the Total Loss Valuation
If you believe your car's valuation is too low, do not simply accept the first offer. Follow these steps to challenge it effectively:
- Request a copy of the valuation report: Insurers must provide it upon request. Review it for errors or omissions.
- Gather evidence: Collect maintenance records, receipts for upgrades, and listings for comparable vehicles in your area.
- Contact the adjuster: Present your evidence clearly and ask for a revised offer. Keep a record of all communications.
- Escalate if needed: If the adjuster is unresponsive, ask to speak with a supervisor or file a complaint with your state's insurance department.
- Consider an independent appraisal: If negotiations stall, invoke the appraisal clause if your policy allows it.
Remember, you have rights as a policyholder. Insurance companies are regulated by state law, and they must treat you fairly. If you feel you are being treated unfairly, do not hesitate to seek help from a consumer protection agency or an attorney experienced in insurance disputes.
Understanding how total loss car accident claim payouts are calculated empowers you to advocate for a fair settlement. By knowing the difference between ACV and replacement cost, reviewing valuation reports, and negotiating strategically, you can maximize your recovery and avoid being shortchanged. If you need assistance connecting with a qualified attorney, consider a free case review through a trusted referral service.