Does Homeowners Insurance Cover a Slip and Fall on My Property?
Does homeowners insurance cover a slip and fall on my property? Get clarity on liability and MedPay coverage. Call (833)-632-1198 for a free case evaluation.
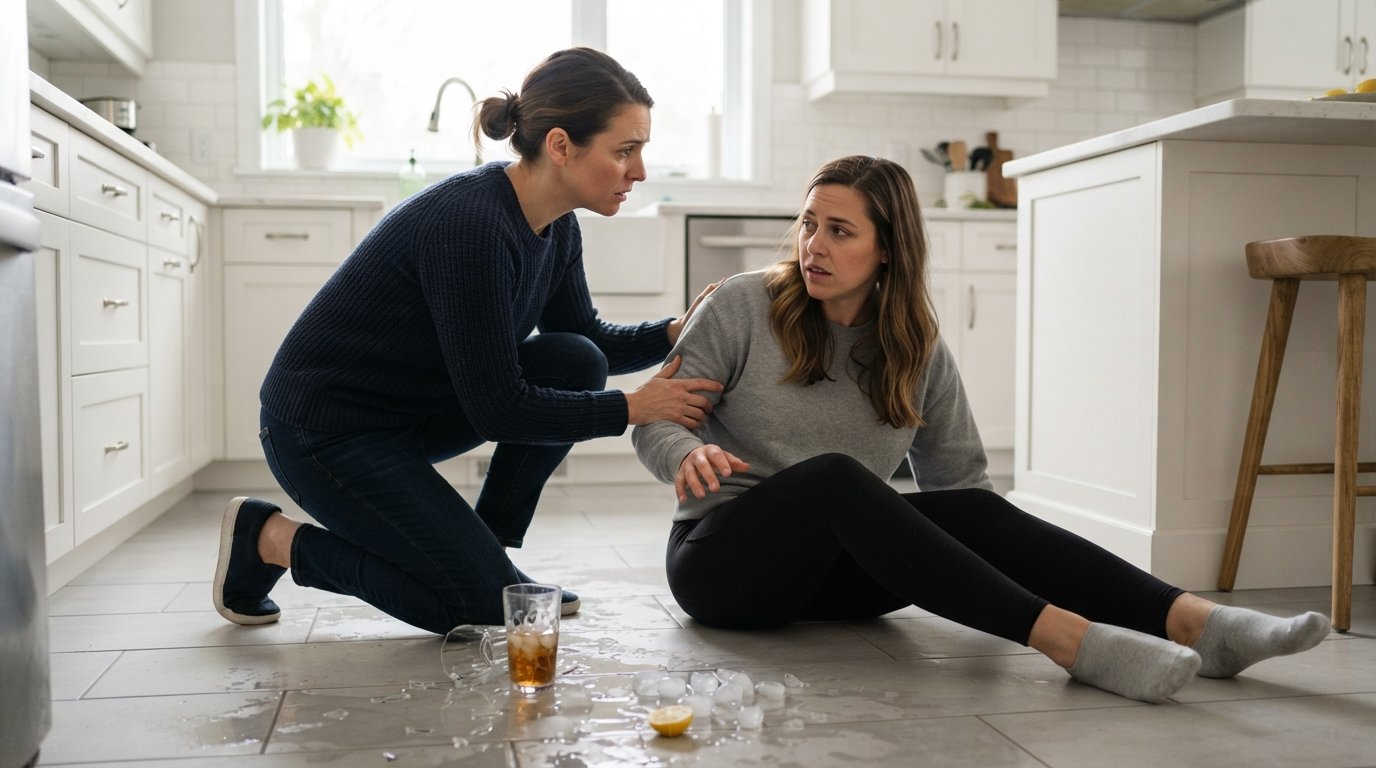
A guest slips on your wet kitchen floor, a delivery driver trips on a cracked walkway, or a neighbor falls down your stairs. In that moment, panic sets in: will your homeowners insurance cover a slip and fall on my property, or are you facing a financial nightmare? The answer is not a simple yes or no. It depends on the specific circumstances, the type of policy you hold, and how the claim is handled. Understanding the nuances of personal liability and medical payments coverage can mean the difference between a smooth claims process and a protracted legal battle. This guide breaks down exactly how homeowners insurance responds to slip and fall incidents, what steps you must take immediately after an accident, and how to protect your financial interests if an insurer denies your claim.
Personal Liability Coverage: The Core of Slip and Fall Protection
When someone is injured on your property, the primary component of your homeowners policy that responds is personal liability coverage (Coverage E). This coverage is designed to protect you financially if you are legally responsible for bodily injury or property damage to a third party. It typically pays for the injured person's medical bills, lost wages, and pain and suffering, up to your policy limit. It also covers your legal defense costs if the injured party sues you, even if the lawsuit is fraudulent or groundless. Standard policies often start at $100,000 in liability coverage, but many experts recommend increasing that limit to $300,000 or more, especially if you have significant assets to protect. For a deeper look at what happens when claims exceed these limits, see our guide on when damages exceed insurance coverage.
The key phrase here is "legally responsible." Your insurer will only pay if you are found to be at fault for the injury. If the injured person was trespassing, or if the accident was entirely their own fault, your liability coverage may not apply. However, the determination of fault is not always clear-cut. Homeowners have a duty of care to maintain safe premises, and if a hazard was known or should have been known, you could be held liable. For example, if you left a garden hose across the sidewalk and a guest trips over it, you are likely at fault. If a meter reader ignores a clear "Beware of Dog" sign and gets bitten, the liability might be shared or denied. Insurers investigate these details meticulously, so accurate documentation is crucial.
Medical Payments Coverage: No-Fault Guest Injury Coverage
Separate from liability coverage is medical payments coverage (Coverage F), sometimes called MedPay. This coverage pays for medical expenses for guests who are injured on your property, regardless of who was at fault. It is a no-fault benefit, meaning the injured person does not have to prove you were negligent to receive payment. MedPay typically covers reasonable and necessary medical expenses, such as ambulance rides, hospital visits, X-rays, and surgery, up to a limit (often $1,000 to $5,000). This coverage is a goodwill gesture that can help avoid a lawsuit by promptly paying for minor injuries. It also covers injuries to you and your family members, which is a distinct advantage.
However, MedPay has limitations. It does not cover lost wages, pain and suffering, or other non-medical damages. It also does not apply if the injured person is a regular resident of your household (though some policies extend coverage to domestic employees). If the injured party's medical bills exceed the MedPay limit, they may then pursue a liability claim against you. Understanding the interplay between these two coverages is essential. For instance, if a guest slips and falls, MedPay can immediately address their medical needs, while liability coverage stands ready if they decide to sue for additional damages.
How Fault Is Determined for a Property Injury
Determining fault in a slip and fall case is rarely straightforward. The legal standard is typically negligence, which requires proving four elements: duty, breach, causation, and damages. As a homeowner, you have a duty to maintain your property in a reasonably safe condition. A breach occurs if you fail to fix a known hazard or fail to warn guests about it. Causation means the breach directly caused the injury. Damages are the resulting medical bills and other losses. The injured person must prove all four elements to hold you liable. Insurers and courts consider various factors, including the length of time the hazard existed, whether it was obvious, and whether the injured person was paying attention.
Comparative negligence rules can also come into play. If the injured person was partially at fault (e.g., they were running, looking at their phone, or ignored a warning sign), their recovery may be reduced or barred, depending on your state's laws. Some states follow pure comparative negligence, where damages are reduced by the plaintiff's percentage of fault. Others follow modified comparative negligence, where a plaintiff cannot recover if they are more than 50% at fault. A few states still use contributory negligence, which bars recovery if the plaintiff is at fault at all. These rules significantly impact how an insurer evaluates a claim. For example, if a guest slips on a wet floor but was running through the house, the insurer might argue the guest's own negligence contributed to the injury, reducing the payout.
Steps to Take Immediately After a Slip and Fall on Your Property
What you do in the minutes and hours after an accident can profoundly affect the insurance claim. Your first priority should always be the safety and well-being of the injured person. Call for medical help if needed, and administer first aid if you are trained. Once the immediate danger is addressed, you need to document the scene thoroughly. This documentation will be your best defense against exaggerated or fraudulent claims. Take photos of the hazard (e.g., the wet floor, the uneven pavement), the surrounding area, and any visible injuries. If there were witnesses, collect their names and contact information. Write down your own account of what happened while it is fresh in your mind.
Here is a checklist of steps to follow:
- Ensure safety and call for medical help. Do not move an injured person unless they are in immediate danger.
- Document the scene. Take photos and videos of the hazard, the lighting, and the injured person's position. Preserve any evidence (e.g., the torn carpet, the broken step).
- Gather witness information. Get names, phone numbers, and addresses of anyone who saw the incident.
- Notify your insurer promptly. Report the incident to your homeowners insurance company as soon as possible, even if you think it is minor. Most policies require prompt notice.
- Avoid admitting fault. Be sympathetic, but do not say "I'm sorry, it was my fault" or "I should have fixed that." These statements can be used against you.
After you have documented the scene and notified your insurer, cooperate fully with the claims adjuster. Provide the documentation you gathered and answer questions truthfully, but stick to the facts. Do not speculate or guess. If the injured person contacts you directly, refer them to your insurance company. Do not offer to pay their medical bills out of pocket or make any promises. Your insurer will handle the communication and negotiation. If you feel overwhelmed, consider consulting an attorney who specializes in insurance claims or premises liability. A legal professional can help you navigate the process and protect your rights.
What to Do When an Insurer Denies a Slip and Fall Claim
It is not uncommon for homeowners insurers to deny slip and fall claims, especially if they believe the homeowner was not at fault or the injury was pre-existing. A denial can be frustrating, but it is not the end of the road. The first step is to understand the reason for the denial. The insurer must provide a written explanation, citing the policy language or facts that led to their decision. Common reasons for denial include lack of liability (the insurer believes someone else was at fault), failure to maintain the property (e.g., the homeowner knew about a hazard and did nothing), or policy exclusions (e.g., the injury occurred during a business activity). Once you understand the reason, you can gather additional evidence to challenge the decision.
If you believe the denial is wrong, you can appeal the decision. Write a formal letter to the insurer, including any new evidence, witness statements, or photos that support your case. Be clear and concise, and reference specific policy provisions. If the insurer still refuses to pay, you can file a complaint with your state's insurance department. This regulator oversees insurance companies and can investigate unfair claims practices. Another option is to hire a public adjuster or an attorney to negotiate on your behalf. An attorney can review the policy, assess the strength of your case, and potentially sue the insurer for bad faith if they wrongfully denied the claim. Remember, your insurer has a duty to act in good faith, and a denial that lacks a reasonable basis could expose them to additional liability.
In some cases, the denial may be legitimate. For example, if the injured person was trespassing or if the injury was caused by a hazard that was open and obvious, the insurer may have grounds to deny. In such situations, you may still face a lawsuit from the injured party. Your liability coverage includes legal defense costs, so your insurer will provide an attorney to defend you even if they deny coverage for the damages. However, if the denial is upheld, you could be personally responsible for any judgment. This is why it is crucial to have adequate liability limits and to consider an umbrella policy for additional protection. For complex legal disputes, consulting a legal professional is wise. Legal information sites like AttorneyLawsuit offer resources on attorney-related lawsuits and consumer guidance that can help you understand your options.
Why You Should Never Admit Fault to the Injured Person
Admitting fault, even casually, can be disastrous for your insurance claim and your personal finances. Statements like "I'm so sorry, I knew that step was loose" or "It's my fault, I should have mopped that up" can be used as evidence of negligence in a lawsuit. Insurers are trained to ask leading questions, and the injured person's attorney will likely seize on any admission. Even if you feel guilty or want to be polite, resist the urge to apologize for the accident. You can express concern for their well-being (e.g., "I hope you're okay, can I call someone for you?") without accepting responsibility. If the injured person asks why the accident happened, simply say, "I'm not sure, but let's get you medical attention and report this to my insurance company."
Remember that your insurer is on your side when it comes to defending against a claim, but they are not your friend. They will use your words against you if it helps them deny or minimize the claim. The best approach is to be cooperative but cautious. Provide factual information to the claims adjuster, but do not speculate about fault or offer opinions. If you are unsure what to say, consult an attorney before making any statements. Protecting your words is as important as protecting your property.
Premises Liability Claim vs. Guest Injury Claim: What Is the Difference?
Not all slip and fall incidents are treated equally under the law. A premises liability claim is a legal action brought by someone who was injured on your property due to a dangerous condition. It requires proving negligence, as discussed earlier. A guest injury claim, on the other hand, is a broader term that can encompass injuries to social guests, invitees (e.g., delivery workers, repair technicians), and licensees. The key difference lies in the legal status of the injured person and the duty of care you owe them. Invitees are owed the highest duty of care, as they are on your property for your benefit (e.g., a customer). Licensees are owed a duty to warn of known hazards. Trespassers are owed the lowest duty, typically only to avoid willful or wanton harm.
Insurance policies often use the term "guest" broadly, but the legal distinctions matter when determining fault and coverage. For example, if a delivery driver (invitee) trips on a broken step, you may be liable because you should have inspected the property and fixed the hazard. If a friend (licensee) trips on the same step, you may only be liable if you knew about the hazard and failed to warn them. These nuances affect how an insurer evaluates a claim. It is also important to note that some policies exclude coverage for injuries to certain classes of people, such as independent contractors or business invitees, if the injury occurs during a business activity. Always review your policy's definitions and exclusions to understand who is covered.
Final Thoughts on Protecting Yourself and Your Guests
Navigating a slip and fall claim on your property can be stressful, but understanding your homeowners insurance coverage is the first step toward protecting your financial future. Personal liability and medical payments coverage are your primary tools, but they have limits and conditions. By documenting incidents thoroughly, avoiding admissions of fault, and cooperating with your insurer, you can strengthen your position. If a claim is denied, do not give up: appeal the decision, gather evidence, and consider professional guidance. Ultimately, the best defense is prevention. Regularly inspect your property for hazards, repair issues promptly, and maintain adequate liability limits. For personalized legal advice and to explore your options, you can request a free case evaluation from a qualified attorney through LawyerOffer. Call (833)-632-1198 to speak with a representative today.