Can You Sue a Driver With No Assets After an Accident?
Yes, you can sue a driver with no assets after an accident, but recovery often depends on UM/UIM coverage. Call (833)-632-1198 for a free case review.
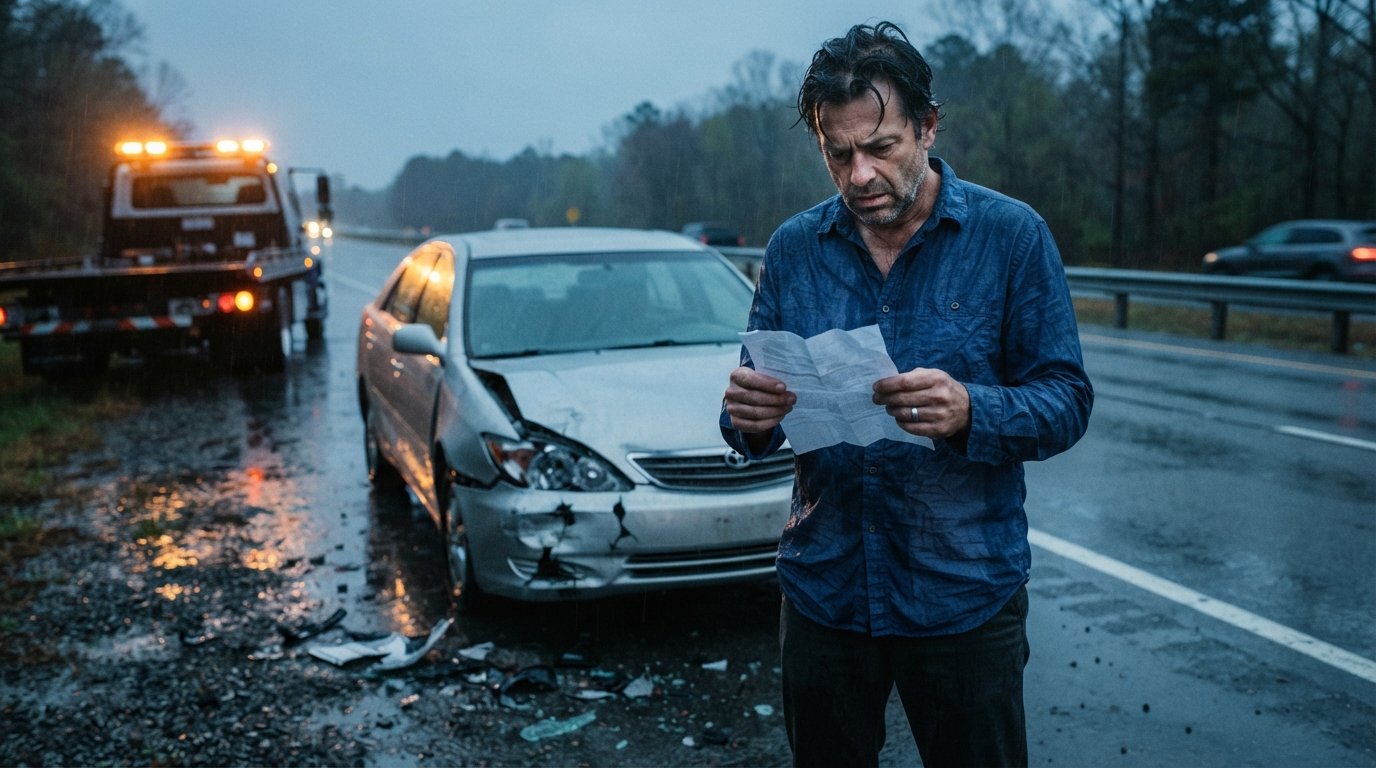
The screech of tires, the crunch of metal, and then the sickening realization that the at-fault driver has no insurance, no savings, and no property to speak of. It is a scenario that plays out every day on American roads, and it leaves injured victims feeling trapped between mounting medical bills and a legal system that seems to offer no real remedy. If you are asking yourself whether you can sue a driver with no assets after an accident, the short answer is yes, you can file a lawsuit against virtually anyone who caused you harm. The more important question is whether that lawsuit will actually put money in your pocket, and the answer depends on a web of insurance policies, state laws, and collection strategies that most people never think about until they are forced to.
Understanding the difference between legal liability and financial recoverability is the key to navigating this frustrating situation. A driver who runs a red light is legally liable for your injuries, but if that driver has nothing more than a beat-up car and a negative bank balance, a judgment against them may be worth less than the paper it is printed on. Fortunately, there are often hidden sources of compensation that accident victims overlook, and a strategic approach can sometimes turn a seemingly hopeless claim into a meaningful recovery. This guide walks through the practical realities, the insurance angles, and the litigation decisions that matter when the at-fault driver has no assets.
The Legal Right to Sue Does Not Depend on the Defendant's Bank Account
Every state gives injured people the right to file a civil lawsuit against a negligent driver who caused them harm, and that right does not evaporate simply because the defendant is broke. The courthouse doors are open regardless of the defendant's financial status. However, the practical value of a lawsuit is a different matter entirely, and experienced attorneys evaluate cases based on collectability, meaning whether there is a realistic source of money to satisfy a judgment or settlement. This is why many lawyers will still take a case against an uninsured driver, but only after a thorough investigation into every possible insurance policy and asset that might apply.
When you sue a driver with no assets after an accident, you are essentially pursuing two separate goals at once. The first is establishing liability through a judgment, which can have long-term consequences for the defendant and may be collectible years later if their financial situation improves. The second and more immediate goal is unlocking insurance coverage, either from the defendant's own policy (if any), your own policy through uninsured or underinsured motorist coverage, or a commercial or umbrella policy that might extend to the driver. Most of the real money in these cases comes from insurance contracts, not from the defendant's personal savings.
It is also worth noting that "no assets" is often a subjective claim made by a defendant who has little incentive to be honest. People hide assets, fail to mention retirement accounts, or simply do not understand what counts as an asset. A skilled attorney can conduct discovery, including depositions and financial records requests, to verify whether the defendant truly has nothing. Sometimes the defendant has a pending inheritance, a tax refund, or equity in a home that is not obvious from a casual conversation at the accident scene.
Uninsured and Underinsured Motorist Coverage: Your Hidden Safety Net
The single most important thing to do after an accident with an apparently judgment-proof driver is to review your own auto insurance policy. Most states require insurers to offer uninsured motorist coverage (UM) and underinsured motorist coverage (UIM), though some states allow you to reject it in writing. UM coverage steps in when the at-fault driver has no insurance at all, while UIM coverage applies when the at-fault driver has some insurance but not enough to cover your damages. These coverages exist precisely to address the scenario where you can sue a driver with no assets after an accident but cannot collect from them directly.
UM and UIM claims are made against your own insurer, and they are treated much like a claim against the other driver, meaning you still need to prove that the other driver was at fault and that your injuries are worth a certain amount. Many people are surprised to learn that their own insurer will defend these claims vigorously, even though the policyholder is the victim. Having legal representation in this process is important because insurers know that unrepresented claimants often accept lowball offers to avoid the hassle of a dispute. A personal injury attorney can handle the negotiation and, if necessary, file suit against the insurer for bad faith or breach of contract.
There are limits to UM and UIM coverage, of course, and those limits are tied to the amount you purchased. If you carried the minimum coverage required by your state, your recovery may be modest. However, some policies include stacking provisions that allow you to combine coverage across multiple vehicles on the same policy, which can substantially increase the available funds. An attorney can review your declarations page and explain exactly how much coverage is available and how stacking might apply to your situation.
Other Insurance Policies That May Apply to the At-Fault Driver
Beyond the driver's own auto policy, there may be other insurance contracts that respond to the accident. If the at-fault driver was working at the time of the crash, their employer may be vicariously liable, and the employer's commercial auto policy or general liability policy could provide coverage. This is common in accidents involving delivery drivers, truck drivers, and employees running errands for their company. Commercial policies often carry much higher limits than personal auto policies, so identifying an employment relationship can dramatically change the value of a claim.
Another often-overlooked source is an umbrella policy held by the at-fault driver or a member of their household. Umbrella policies provide excess liability coverage above the underlying auto and homeowners policies, often in increments of one million dollars or more. A driver who appears to have no assets may still be covered by a wealthy parent's or spouse's umbrella policy if they live in the same household or drive a vehicle covered by that policy. Attorneys routinely send letters to every insurer that might have a duty to defend or indemnify the at-fault driver, and those letters often uncover coverage that the victim never knew existed.
Homeowners and renters insurance can also come into play in certain circumstances, particularly if the accident involved a vehicle owned by the household or if the driver was operating a borrowed vehicle with permission. Some homeowners policies extend liability coverage to the insured's use of non-owned vehicles, though exclusions vary widely. The lesson here is that a thorough insurance investigation is essential before concluding that a driver has no assets. What looks like a dead end at first glance often turns into a viable claim once all policies are identified.
How a Lawsuit Against an Uninsured Driver Actually Works
If you decide to proceed with a lawsuit against the driver personally, the process follows the same general path as any other personal injury case. Your attorney files a complaint in the appropriate court, the defendant is served with notice, and the case moves through discovery, pre-trial motions, and potentially trial. If you win, the court enters a judgment in your favor for a specific dollar amount. The judgment is a legal determination that the defendant owes you money, but it is not a guarantee of payment. Collecting on that judgment is a separate process that requires its own strategy.
Many defendants in these cases simply do not show up to court, which results in a default judgment against them. A default judgment can be useful because it establishes the debt and starts the clock on post-judgment collection remedies. However, it also means the defendant may not have participated in discovery, so you may have limited information about their assets. Attorneys sometimes use post-judgment discovery, including debtor examinations, to compel the defendant to disclose bank accounts, employment, and property under oath. Lying at a debtor examination can result in contempt of court, which gives the defendant a strong incentive to be truthful.
It is important to understand that even a modest recovery can be valuable. If the defendant has a job, you may be able to garnish a portion of their wages. If they own a vehicle or other property, you may be able to place a lien on it. If they receive a tax refund or an inheritance, you may be able to intercept those funds. These collection methods are slow and often yield less than the full judgment, but they can provide some compensation over time. An attorney can advise you on which collection strategies are worthwhile given the defendant's circumstances.
Judgment Collection Options After You Win
Once you have a judgment, the law gives you several tools to collect. The availability of each tool depends on state law, but the most common methods include wage garnishment, bank account levies, property liens, and judgment liens on real estate. Wage garnishment allows you to take a percentage of the defendant's disposable income each pay period, subject to federal and state limits designed to protect a basic living wage. Bank levies allow you to seize funds from the defendant's accounts, though certain funds, such as Social Security benefits, are exempt.
Property liens are another option. If the defendant owns real estate, you can record a judgment lien that attaches to the property and must be paid off before the property can be sold or refinanced. Even if the defendant has no immediate plans to sell, the lien can remain in place for years and may eventually produce a recovery. In some states, judgment liens can last for a decade or more and can be renewed. This long-tail approach is one reason why attorneys sometimes pursue judgments even when the defendant appears to have no current assets.
A less common but sometimes effective strategy is to force the sale of certain non-exempt property. However, most states provide generous exemptions for a primary residence, a vehicle, and basic household goods, which limits the practical value of this approach. The bottom line is that collection is a fact-specific inquiry, and the right strategy depends on what the defendant owns, earns, and expects to receive in the future. A lawyer who handles these cases regularly can assess whether collection efforts are likely to pay off.
Why a Settlement May Be Limited by Available Coverage
In most personal injury cases, the settlement value is capped by the amount of insurance coverage available. This is a reality that surprises many victims who assume that the severity of their injuries alone determines the value of their claim. Insurance companies pay what their policies require and little more, and they are not obligated to satisfy a judgment out of their own corporate funds beyond the policy limits. This means that a catastrophic injury caused by a driver with a minimum-limits policy may settle for far less than the victim's actual damages.
This dynamic is why identifying every possible policy is so important. If the at-fault driver has a twenty-five thousand dollar policy but lives with a parent who has a two million dollar umbrella policy that covers the driver, the case may be worth dramatically more. Similarly, if the driver was acting within the scope of their employment, the employer's commercial policy may provide substantial coverage. Attorneys who handle uninsured and underinsured motorist cases are trained to look for these coverage layers, and they often negotiate with multiple insurers simultaneously.
When coverage is truly limited, a settlement may still be the best available outcome. Taking a case to trial against an uninsured driver with no assets can result in a large judgment that is never paid, while a settlement with the available insurer puts money in the victim's hands relatively quickly. The decision between settling and litigating should be made with a clear understanding of the defendant's financial picture and the likelihood of collection. This is one area where experienced legal counsel makes a significant difference.
It is also worth remembering that social media activity can undermine an otherwise strong claim, even when the defendant has limited assets. A single post showing you hiking or playing sports can be used to challenge your injuries, so it is wise to review your privacy settings and avoid discussing the accident online. Our guide on how social media can hurt your injury claim explains the risks in more detail.
When Litigation Still Makes Sense Despite Limited Assets
Even when the defendant has no assets, there are several situations where filing a lawsuit is still a smart move. First, litigation may be necessary to trigger UM or UIM coverage. Some insurers require a lawsuit or at least a formal demand before they will pay, and a judgment against the uninsured driver can establish the amount of damages that your own policy must cover. Second, a lawsuit preserves your rights and prevents the statute of limitations from expiring while you investigate coverage. Third, litigation can uncover assets that were not apparent before discovery, including hidden accounts or future income streams.
Another consideration is the possibility that the defendant will come into money later. Judgments can often be renewed and remain enforceable for many years, which means that if the defendant inherits money, wins the lottery, or sells a property, you may be able to collect. This long-term approach is not right for everyone, but it is a factor that some victims choose to weigh. An attorney can explain the relevant statute of limitations and judgment renewal rules in your state.
Finally, there is a deterrent value to holding negligent drivers accountable. A judgment, even an uncollected one, can affect the defendant's credit and serve as a lasting reminder of their responsibility. Some victims find closure in the legal process itself, regardless of the financial outcome. These personal considerations are valid and should be discussed openly with your lawyer.
If you are dealing with a legal dispute involving an attorney or law firm, resources such as AttorneyLawsuit provide information on legal malpractice and fee disputes that may be relevant to your situation.
Practical Steps to Take After an Accident With an Uninsured Driver
The steps you take in the days and weeks after the accident can significantly affect your ability to recover, even when the at-fault driver appears to have nothing. The first priority is always medical treatment, both for your health and for the documentation it creates. Delays in treatment are often used by insurers to argue that your injuries were not serious or were caused by something else. Follow your doctor's recommendations and keep records of every appointment, prescription, and procedure.
Next, report the accident to your own insurer promptly and cooperate with their investigation, but be careful about giving recorded statements before you understand your coverage. You are generally required to notify your insurer of an accident, but you are not required to accept a quick settlement or to provide a statement that could later be used against you. It is often wise to consult an attorney before speaking with any adjuster, including your own. The following steps summarize a sensible approach:
- Seek medical attention immediately and document all injuries and treatment.
- Report the accident to your insurer and confirm your UM and UIM coverage limits.
- Gather evidence, including photos, witness statements, and the police report.
- Identify every potential insurance policy, including commercial and umbrella policies.
- Consult a personal injury attorney before accepting any settlement offer.
Each of these steps builds a record that supports your claim and protects your rights. Evidence collection is especially important because memories fade and witnesses become harder to reach over time. A police report that identifies the at-fault driver and any citations issued can be powerful evidence of liability. If the driver was uninsured, the report may also note that fact, which supports a UM claim.
Finally, be cautious about signing anything from the other driver or their insurer without legal review. Releases and settlement agreements can waive your right to pursue additional compensation, including from your own UM coverage. An attorney can review any documents and explain the consequences before you sign. The stakes are high enough that a brief consultation is almost always worthwhile.
How a Lawyer Can Help When the Defendant Has No Assets
An experienced personal injury attorney brings several advantages to a case involving an uninsured or judgment-proof driver. The most important is a systematic approach to identifying insurance coverage. Attorneys know how to request declarations pages, send coverage letters, and negotiate with multiple insurers at once. They also understand the nuances of UM and UIM claims and can push back when an insurer tries to undervalue your damages. If you are considering whether to sue a driver with no assets after an accident, a free case review can help you understand your options without any upfront cost.
Attorneys also handle the litigation and collection process if a lawsuit becomes necessary. They can file the complaint, conduct discovery, and pursue post-judgment remedies like garnishment and liens. Many personal injury lawyers work on a contingency fee basis, meaning they are paid a percentage of the recovery and do not charge upfront fees. This arrangement makes legal representation accessible even when the defendant has limited resources. A reputable platform like LawyerOffer can connect you with attorneys who handle these cases and offer confidential case evaluations at no cost.
The decision to sue a driver with no assets after an accident is ultimately a personal one, but it should be made with full information about the available insurance, the defendant's financial circumstances, and the realistic prospects for collection. With the right strategy, many victims recover far more than they expected, often from their own policies or from commercial coverage they never knew existed. The worst outcome is to give up before investigating those possibilities.
If you are facing mounting bills and an uncooperative at-fault driver, do not assume that your case is worthless. Reach out for a confidential case evaluation and let a qualified attorney review your insurance policies, investigate the accident, and explain your legal options. The path forward may be clearer than you think, and the sooner you act, the more options remain available.