What Is a Bad Faith Insurance Claim and How Do I File One?
Frustrated by an insurer's delay or lowball offer? Learn what is a bad faith insurance claim and how to file one. Call (833)-632-1198 for a free case review.
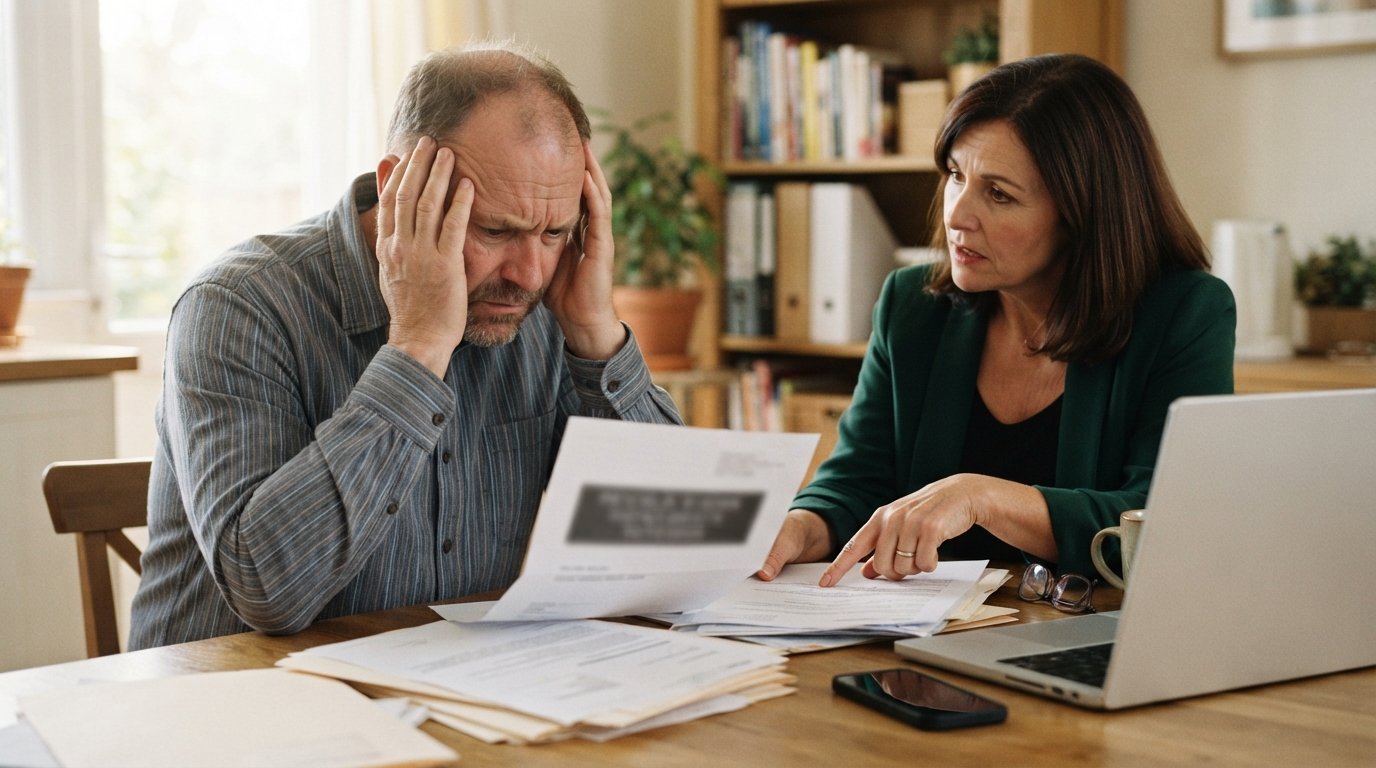
You pay your premiums faithfully, expecting your insurer to be there when you need them. But when disaster strikes, the check doesn't arrive, the offer is insultingly low, or the adjuster simply stops returning your calls. In these moments, you may wonder: is this just bad luck, or is it bad faith? Understanding what is a bad faith insurance claim and how do I file one is the first step toward holding your insurer accountable and securing the compensation you deserve.
Bad faith insurance claims arise when an insurer unreasonably delays, denies, or undervalues a valid claim. It's a breach of the fundamental covenant of good faith and fair dealing that every insurance policy carries. If you suspect your insurer is acting in bad faith, you have options. This guide will walk you through the definitions, the warning signs, the evidence you need, and the steps to file a claim, whether through a regulatory complaint or a civil lawsuit. For those considering legal action, resources like CarInjuryAccident can connect you with attorneys who specialize in these complex disputes.
Understanding Bad Faith in Insurance
Insurance is a contract built on trust. When you buy a policy, you're not just purchasing a product; you're entering a relationship where the insurer promises to act fairly and promptly when you file a claim. The legal principle behind this is the implied covenant of good faith and fair dealing. This covenant means that neither party will do anything to unfairly undermine the other's right to receive the benefits of the contract. When an insurer violates this duty, it commits bad faith.
Bad faith is more than just a disagreement over the value of a claim. It involves unreasonable conduct: denying a claim without a proper investigation, delaying payment without justification, or offering a settlement that is far below what the evidence supports. It can also include failing to communicate, misrepresenting policy terms, or ignoring evidence that clearly supports your claim. The key is that the insurer's actions must be unreasonable and often demonstrate a conscious disregard for your rights. Understanding these nuances is essential to recognizing when you have a potential bad faith claim.
First-Party vs. Third-Party Bad Faith
Bad faith claims generally fall into two categories: first-party and third-party. In a first-party bad faith claim, you are the policyholder, and you are making a claim directly against your own insurer for benefits you are entitled to under your policy. Common examples include claims for property damage, health insurance benefits, or uninsured motorist coverage. The insurer's duty is to you, its insured.
In a third-party bad faith claim, the situation is different. You are the insured, but a third party (someone else) has filed a claim against you. Your insurer has a duty to defend you and to settle the claim within your policy limits if a reasonable opportunity arises. If the insurer unreasonably fails to settle within limits, and a judgment is later entered against you for more than the policy limits, the insurer may be liable for the entire judgment, including the excess amount. This is known as a third-party bad faith claim. Understanding which type applies to your situation is crucial for building your case.
Common Examples of Bad Faith Insurance Practices
Insurance companies are businesses, and sometimes they prioritize profits over policyholders. While not every delay or low offer is bad faith, certain patterns of behavior are red flags. Recognizing these examples can help you determine if you have a claim. Here are some of the most common tactics insurers use that may constitute bad faith.
- Lowball settlement offers: Offering an amount that is clearly inadequate based on the evidence, without a reasonable explanation, is a classic sign of bad faith. This often happens when the insurer fails to thoroughly investigate or ignores medical records and expert opinions.
- Unreasonable delays: Missing deadlines, failing to respond to communications, or dragging out the investigation without justification can be a tactic to pressure you into accepting a lower settlement. Insurance regulations often mandate specific timeframes for responding to claims.
- Ignoring evidence: If you provide documentation, witness statements, or expert reports that support your claim, and the insurer disregards them, that's a red flag. A thorough investigation is a fundamental duty.
- Denying a claim without a valid reason: Denying a claim based on a policy exclusion that doesn't apply, or misrepresenting the facts, is a clear example of bad faith. Insurers must provide a reasonable explanation for any denial.
- Failing to communicate: Not keeping you informed about the status of your claim or not responding to your inquiries can be a breach of the duty of good faith.
These are just a few examples. Bad faith can also include failing to defend you in a lawsuit, not informing you of settlement offers in a third-party claim, or making threats. If you've experienced any of these behaviors, it's worth documenting them and seeking legal advice. In our guide on how AI is used in insurance claim processing, we explain how automated systems can sometimes contribute to delays or errors, which may be relevant to your case.
How to Build Evidence for a Bad Faith Claim
Building a successful bad faith claim requires solid evidence. The burden is on you to show that the insurer acted unreasonably. From the moment you file your claim, you should start keeping a detailed record of all interactions. This documentation will be invaluable if you need to file a complaint or lawsuit.
Here are the key types of evidence you should collect:
- All communications: Save copies of letters, emails, and text messages. Keep a log of phone calls, including the date, time, who you spoke with, and a summary of what was said. If you record calls (check your state's consent laws), keep those recordings.
- Your policy documents: Have a complete copy of your insurance policy, including all endorsements and amendments. This will help you understand your rights and the insurer's obligations.
- Proof of loss: Document all your damages with receipts, invoices, medical records, repair estimates, and photos or videos of the damage. The more detailed, the better.
- Correspondence with the insurer: Keep every letter and email you receive from the insurer. Note any deadlines they mention and whether they meet them.
- Evidence you provided: Keep copies of everything you sent to the insurer, including witness statements, expert reports, and any other supporting documents.
- Notes on delays: If the insurer is late in responding or paying, document the dates and any excuses they give.
This evidence will not only support your bad faith claim but also help your attorney evaluate the strength of your case. Remember, the more organized and comprehensive your records, the easier it will be to demonstrate a pattern of unreasonable conduct.
Filing a Bad Faith Claim: Regulatory Complaint vs. Civil Lawsuit
Once you've gathered evidence, you have two main avenues to pursue a bad faith claim: filing a complaint with your state's insurance department or filing a civil lawsuit against the insurer. Each has its own process, advantages, and limitations. In many cases, policyholders pursue both simultaneously or sequentially.
Filing a Complaint with the State Insurance Department
Every state has an insurance regulatory agency that oversees insurers and handles consumer complaints. Filing a complaint is often free and can be done online or by mail. The agency will investigate your complaint and may require the insurer to respond. This process can be effective in resolving disputes quickly, especially if the insurer has violated state regulations. However, the agency cannot award you damages; it can only enforce compliance and possibly impose fines on the insurer. It's a good first step, but it may not fully compensate you for your losses.
To file a complaint, you'll typically need to provide your policy information, a detailed description of the issue, and copies of your evidence. The agency will then contact the insurer and facilitate communication. While this process is less formal than a lawsuit, it can still pressure the insurer to act fairly.
Filing a Civil Bad Faith Lawsuit
If the regulatory complaint doesn't resolve the issue, or if your damages are significant, you may consider filing a civil lawsuit. A bad faith lawsuit is a formal legal action in court. You will need an attorney experienced in insurance bad faith law. The lawsuit will allege that the insurer breached its duty of good faith and fair dealing, and you will seek damages.
The litigation process involves pleadings, discovery (where both sides exchange evidence), and possibly trial. It can be time-consuming and expensive, but it's often the only way to recover certain types of damages, such as punitive damages or damages exceeding policy limits. Many attorneys handle bad faith cases on a contingency fee basis, meaning you pay nothing upfront and only pay if you win. This makes legal representation accessible to policyholders.
When choosing between these options, consider the complexity of your case, the amount of damages, and your willingness to engage in a legal battle. An attorney can help you decide the best course of action.
Damages Available in Bad Faith Cases
One of the key reasons to pursue a bad faith claim is the potential to recover damages beyond the policy limits. In a standard breach of contract claim, you can only recover the benefits owed under the policy. But in a bad faith tort claim, you may be entitled to a broader range of damages. These can include:
- Compensatory damages: This includes the amount of the claim you were wrongly denied, plus any consequential damages (such as financial losses caused by the delay, like attorney fees incurred to fight the denial, or lost business opportunities).
- Emotional distress damages: If the insurer's conduct caused you significant emotional distress, you may be able to recover damages for that harm. This is more common in cases involving severe misconduct.
- Punitive damages: In cases where the insurer's conduct was particularly egregious or malicious, the court may award punitive damages to punish the insurer and deter similar behavior. These can be substantial and are not limited by the policy amount.
- Attorney fees and costs: Many states allow policyholders to recover their attorney fees and litigation costs if they prevail in a bad faith lawsuit. This can make it financially feasible to take on a large insurer.
- Damages exceeding policy limits: In third-party bad faith cases, if the insurer unreasonably fails to settle within limits, it may be held liable for the entire judgment against you, even if it exceeds your policy limits. This is a powerful incentive for insurers to act fairly.
These damages can far exceed the original claim amount, which is why insurers often take bad faith allegations seriously. However, proving entitlement to these damages requires strong evidence and skilled legal representation.
Steps to File a Bad Faith Insurance Claim
If you believe your insurer has acted in bad faith, here is a step-by-step guide to filing a claim. Keep in mind that this is a general overview, and consulting with an attorney is highly recommended.
- Document everything: As discussed, gather all evidence, including your policy, communications, and proof of loss. Create a timeline of events.
- Review your policy: Understand what your policy covers and what the insurer's obligations are. Look for any clauses about claim handling and dispute resolution.
- Send a demand letter: Before filing a lawsuit, it's often wise to send a formal demand letter to the insurer outlining your claim and the evidence of bad faith. This may prompt a settlement and is sometimes required before litigation.
- File a complaint with the state insurance department: This is a low-cost way to get the insurer's attention and may lead to a resolution. It also creates a record of your complaint.
- Consult an attorney: An experienced bad faith attorney can evaluate your case, help you decide the best course of action, and represent you in negotiations or litigation. Many offer free consultations.
- File a lawsuit if necessary: If the insurer remains unreasonable, your attorney can file a civil complaint in court. The lawsuit will detail the insurer's bad faith conduct and the damages you seek.
Each step builds on the previous one, and having an attorney by your side can help you navigate the complexities of insurance law. Remember, time limits (statutes of limitations) apply to bad faith claims, so don't delay.
When to Hire a Bad Faith Insurance Attorney
While you can file a regulatory complaint on your own, a bad faith lawsuit is complex and best handled by an attorney. You should consider hiring an attorney if your claim is significant, if the insurer's conduct is egregious, or if you've already tried to resolve the issue without success. Attorneys who specialize in insurance bad faith understand the tactics insurers use and can level the playing field.
Platforms like LawyerOffer can connect you with qualified attorneys who handle bad faith claims. They offer free case reviews and can help you understand your rights. When choosing an attorney, look for someone with experience in insurance law and a track record of success. The CarInjuryAccident platform is another resource that connects individuals with seasoned attorneys specializing in personal injury and insurance disputes.
Don't be intimidated by the thought of taking on a large insurance company. With the right evidence and legal representation, you can hold them accountable and secure the compensation you deserve.
In summary, a bad faith insurance claim is a powerful tool for policyholders who have been treated unfairly. By understanding what constitutes bad faith, documenting your claim thoroughly, and knowing your options for filing, you can protect your rights and pursue the benefits you are owed. Whether you file a regulatory complaint or a civil lawsuit, taking action is the first step toward justice.