Comparative Fault States: How Your Award Shrinks
Comparative fault states reduce your award by your share of blame. Call (833)-632-1198 for a free case review and protect your recovery.
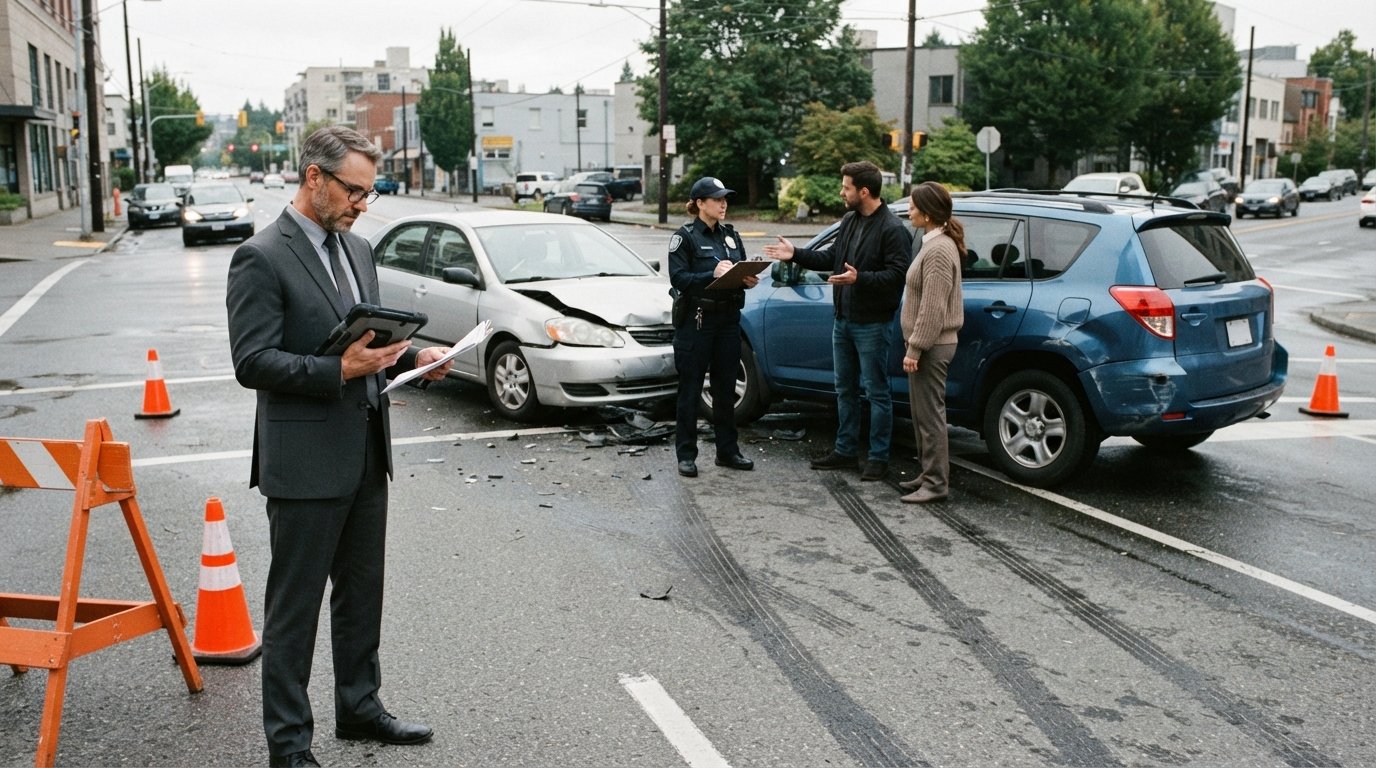
You were hurt in a crash, but the other driver's insurer says you share the blame. Suddenly, the settlement number you had in mind drops, and you are left wondering why. The answer often comes down to one legal concept: comparative fault. In a comparative fault state, your compensation is reduced by your own percentage of responsibility. If a jury decides you were 20 percent at fault, your $100,000 award becomes $80,000. That single rule can mean the difference between a full recovery and a financial shortfall, and it is the reason fault disputes dominate so many injury claims. Understanding how comparative fault works, how fault percentages get assigned, and what you can do to push back on an inflated blame allegation is essential before you accept any offer.
What Is a Comparative Fault State and How Does It Reduce My Award?
A comparative fault state is a jurisdiction that uses a proportional system to divide damages when more than one party contributed to an accident. Instead of the old all-or-nothing rule, where any fault on your part barred recovery entirely, comparative fault lets you recover something even if you were partly responsible. The tradeoff is that your award is reduced by your share of the fault. If you are found 30 percent responsible and your total damages are $50,000, you collect $35,000. The reduction is direct, proportional, and applied after the total damages are calculated.
This rule matters because most accidents are not clean-cut. Rear-end crashes, intersection collisions, and pedestrian incidents frequently involve competing narratives about who did what wrong. Insurers know this, and they use fault allegations strategically. Even a modest fault percentage assigned to you can shave thousands off a claim, and in some states a fault finding above a certain threshold wipes out your right to recover altogether. That is why the question of whether you live in a comparative fault state, and which version of the rule applies, is one of the first things a personal injury attorney evaluates.
The mechanics are straightforward but the consequences are not. Courts and insurers look at the evidence, apply the state's fault rule, and assign percentages that must total 100 across all parties. Your percentage is then multiplied against your damages. The higher your assigned fault, the lower your check. In practical terms, a comparative fault state turns every injury claim into a two-front battle: proving the other party's liability and minimizing your own.
Pure Comparative Fault vs. Modified Comparative Fault
Comparative fault states do not all follow the same formula. The two main versions are pure comparative fault and modified comparative fault, and the difference can be dramatic. In a pure comparative fault state, you can recover damages no matter how much fault you share. Even if you are 90 percent responsible, you can still collect 10 percent of your damages. A handful of states, including California and New York, follow this approach. The upside is that you are never completely barred from recovery. The downside is that a high fault percentage can leave you with a very small award.
Modified comparative fault states impose a threshold. If your fault reaches or exceeds that threshold, you recover nothing. Most modified states use a 51 percent bar: you can recover only if you are 50 percent or less at fault. A smaller group uses a 50 percent bar, meaning you must be less than 50 percent at fault to recover anything. In these states, a fault finding of 51 percent is not just a reduction, it is a complete defense. Insurers in modified states have a strong incentive to push your fault percentage just over the line, because doing so eliminates the claim entirely.
The distinction between these systems is not academic. A victim who would recover $20,000 in a pure comparative state at 80 percent fault recovers nothing in a modified state with a 51 percent bar. If you are unsure which rule applies to your claim, a guide on how comparative negligence laws differ by state can help you identify the framework in your jurisdiction before you negotiate.
How Fault Percentages Are Assigned and Disputed
Fault percentages are not handed down automatically. They are the product of evidence, argument, and sometimes negotiation. In a litigated case, the jury assigns fault to each party based on the evidence presented. In a pre-suit settlement, the insurer and your attorney negotiate over fault as part of the overall valuation. Either way, the percentage is an estimate, and estimates can be influenced. That is why fault disputes are often the most contested part of an injury claim.
Several types of evidence drive fault allocation. Police reports may indicate contributing factors such as speed, distraction, or failure to yield. Traffic camera footage, dashcam video, and eyewitness statements can confirm or contradict those accounts. Vehicle damage patterns and accident reconstruction can show impact angles and speeds. Medical records and statements you made at the scene can also be used, sometimes against you. Insurers comb through all of it looking for anything that supports assigning you a share of the blame.
Common fault allegations in car crash cases include claims that you were speeding, following too closely, failed to signal, were distracted by a phone, or had a mechanical defect you should have addressed. In pedestrian cases, insurers may argue you jaywalked or entered the road unexpectedly. In truck accidents, they may claim you cut off the truck or braked suddenly. Each allegation is a lever the insurer can use to reduce or eliminate your recovery, and each one must be met with evidence and argument.
The 50 Percent and 51 Percent Bar Thresholds
In modified comparative fault states, the threshold is everything. If you are in a 51 percent bar state, you need to be found 50 percent or less at fault to recover. If you are in a 50 percent bar state, you need to be found less than 50 percent at fault. The difference of a single percentage point can decide whether you receive compensation at all. This is why insurers in modified states often anchor their fault allegations just above the threshold, hoping you will accept a low offer rather than risk a trial where a jury might agree.
The threshold also shapes negotiation strategy. If the evidence suggests you are near the line, your attorney may focus on reframing the narrative, producing evidence that shifts blame to the other driver, or challenging the admissibility of evidence the insurer relies on. In some cases, the threat of trial is enough to move an insurer off an aggressive fault position, because insurers know juries can be unpredictable. In others, a pretrial motion or expert testimony is needed to keep the fault question within recoverable territory.
For victims, the practical lesson is that fault percentage is not a fixed fact. It is a conclusion that can be challenged, and in modified states the stakes of that challenge are as high as they get.
Examples: How a 20 Percent Fault Finding Reduces Recovery
Concrete numbers make the rule easier to see. Suppose your total damages, including medical bills, lost wages, and pain and suffering, are $100,000. If the jury or insurer assigns you 20 percent fault, your award becomes $80,000. At 30 percent fault, it drops to $70,000. At 50 percent fault in a 51 percent bar state, you still recover, but only $50,000. At 51 percent fault in that same state, you recover nothing. The same evidence can produce wildly different outcomes depending on how fault is allocated.
Consider a left-turn collision. The other driver claims you ran a red light, while you claim they turned without yielding. If the jury finds the other driver 80 percent at fault and you 20 percent, your $200,000 damages award becomes $160,000. If the jury instead finds you 60 percent at fault, and you are in a 51 percent bar state, you recover zero. The difference between those two outcomes is not the severity of your injuries or the size of your medical bills; it is the fault allocation.
These examples show why fault disputes are worth fighting. A 10 or 20 point swing in fault percentage can translate into tens or hundreds of thousands of dollars. It can also determine whether you recover at all.
Strategies to Counter an Inflated Fault Allegation
If the insurer has assigned you a fault percentage you believe is wrong, you are not without options. The first step is to gather and preserve evidence quickly. Photos of the scene, dashcam or surveillance footage, witness contact information, and your own contemporaneous notes can all help rebut allegations of speeding, distraction, or inattention. The second step is to get an independent expert involved when the physics of the crash matter. Accident reconstruction can challenge claims about speed and impact angle, and medical experts can address causation and the extent of your injuries.
You should also be careful about what you say to insurers. Statements made to an adjuster, even casually, can be used to support a fault allegation. Avoid speculating about speed, timing, or what you were doing in the moments before the crash. Refer the adjuster to your attorney and let the evidence do the talking. If you have not yet retained counsel, a free, confidential case review can help you understand your exposure and identify the strongest counterarguments before you negotiate.
Finally, be prepared to litigate the fault question if the insurer will not budge. In modified comparative fault states, the threat of trial is a real source of leverage, because insurers know a jury might side with you. A well-prepared demand package that addresses fault head-on, rather than ignoring it, often produces better results than a demand that focuses only on damages. If you are searching for attorneys who handle these disputes, a service like AutoInjuryAccident can connect you with participating lawyers for a free case review, and you can compare options before deciding how to proceed.
Comparative fault does not have to mean accepting an unfair reduction. With the right evidence, the right arguments, and the right timing, you can push back on an inflated fault allegation and protect more of your recovery.